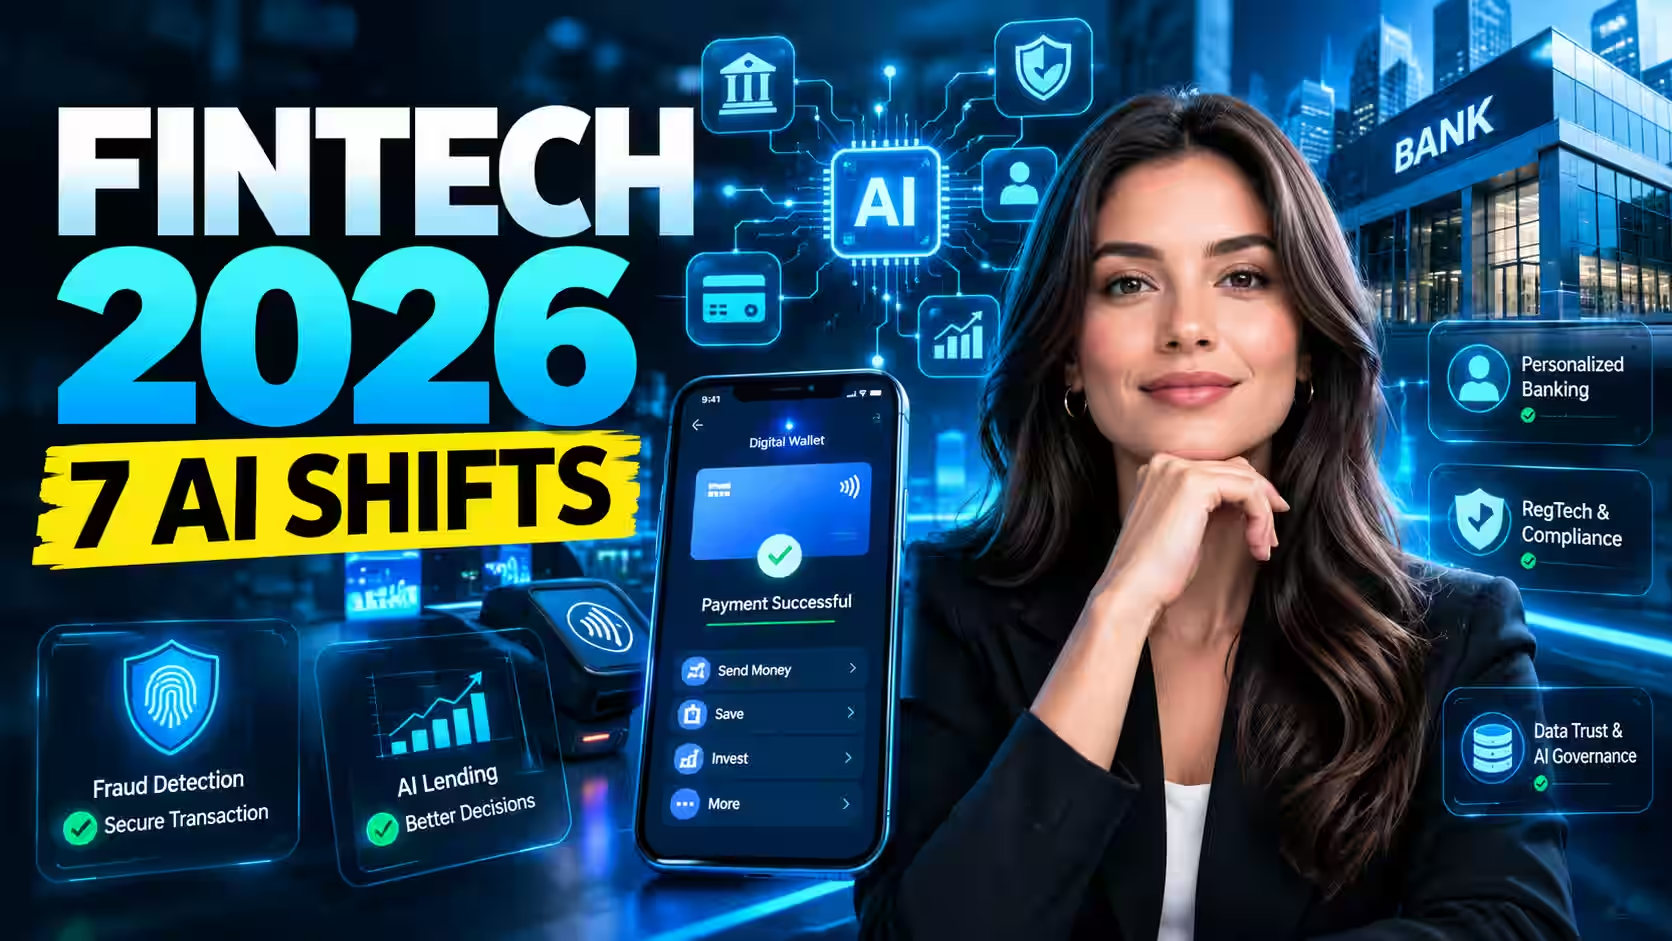
Fintech Trends 2026: 7 AI Shifts Reshaping Banking, Payments, and Lending
Senior Fintech Editor & Analyst · Tech Capital Hub
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering where financial technology, AI, and real business outcomes meet. In this guide, he breaks down the biggest fintech trends of 2026, from AI-powered lending and fraud detection to embedded finance, digital wallets, and AI governance.
Quick answer: The top fintech trends in 2026 are hyper-personalized banking, embedded finance, AI fraud detection, regtech automation, AI-powered lending, smarter digital wallets, and stronger AI governance. Together, they represent a shift from fintech as interface to fintech as intelligence.
Financial technology is moving fast. But not always in the way people expect.
In 2026, the biggest fintech trends aren’t about new apps. They’re about new decision systems — AI layers that are quietly reshaping how money moves, how risk gets assessed, how fraud gets stopped, and how customers experience financial services.
This shift is happening inside large banks and scrappy neobanks alike. It is touching lending, payments, compliance, fraud, and trust. And it’s no longer a story about startups disrupting incumbents. It’s a story about every financial institution racing to build better intelligence into everything they do.
This guide breaks down the 7 most important fintech trends in 2026, explains how AI is driving each one, and offers a practical framework for understanding what’s really changing — and what most trend articles still get wrong.
If you want a deeper look at AI inside consumer banking, read AI in digital banking. For a closer look at AI lending or fraud detection, see BNPL and AI risk assessment and AI fraud detection in finance.
Key Takeaways
- AI is no longer a feature in fintech — it’s the operating layer beneath nearly every product decision.
- The most important changes in 2026 are invisible to end users but felt in faster approvals, better fraud catches, and more relevant offers.
- Embedded finance is moving the customer relationship from banks to platforms.
- Fraud is shifting toward human manipulation — a problem that no privacy setting can solve.
- Governance, explainability, and data rights are now competitive advantages, not just compliance costs.
- The future of fintech is hybrid: banks, fintechs, platforms, and AI systems sharing the value chain.
Table of Contents
The 3-Layer Fintech AI Framework
Most fintech coverage treats trends as a flat list. That misses the structure underneath them.
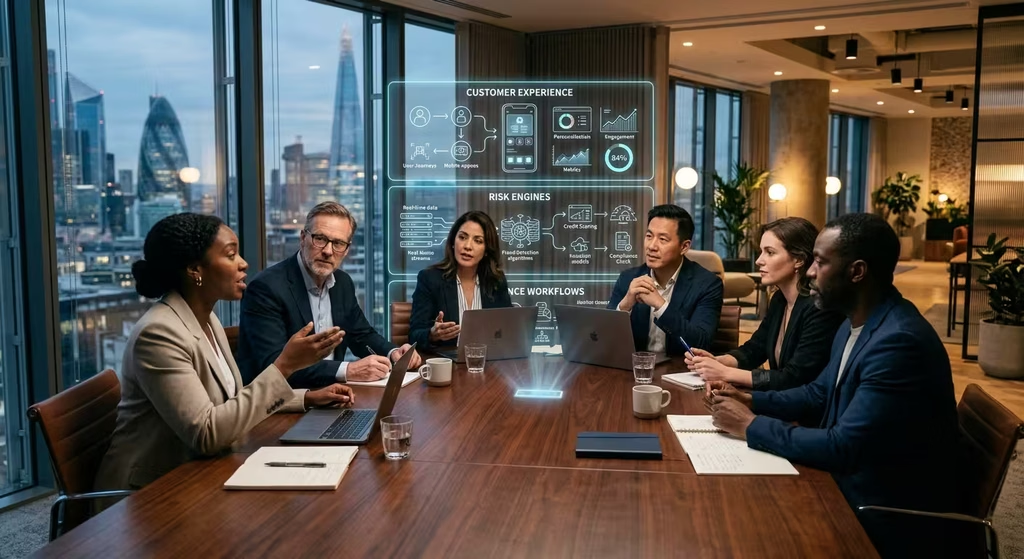
Here’s a more useful way to think about it. AI is reshaping fintech across three distinct layers:
Layer 1 — The Customer-Facing Layer
What users see and feel: personalized alerts, faster approvals, smarter wallets, embedded financial products inside apps they already use.Layer 2 — The Decision-Engine Layer
What runs underneath: credit scoring, fraud detection, AML monitoring, underwriting logic, document verification. Most users never see this layer. But they feel when it works — or when it doesn’t.Layer 3 — The Governance and Trust Layer
What holds it together: explainability, data rights, AI oversight, regulatory compliance, and the trust signals that determine whether users and regulators accept the product.The 7 trends below map across all three layers. Understanding which layer a trend lives in tells you who it affects, how urgent it is, and what the real risk or opportunity looks like.
2026 Fintech Trend Summary Table
| Trend | Layer | What Changed in 2026 | Who It Affects Most | Why It Matters |
|---|---|---|---|---|
| Hyper-personalized banking | Customer-facing | Predictive alerts replace reactive dashboards | Retail banking users | Reduces churn and deepens engagement |
| Embedded finance | Customer-facing | Financial products live inside non-bank platforms | Consumers and merchants | Shifts the customer relationship from bank to platform |
| AI fraud detection | Decision-engine | Behavior-based models replace rule-based systems | Every payment product | $10B+ fraud losses demand smarter detection |
| Regtech and compliance automation | Decision-engine | AI handles monitoring, KYC, and AML at scale | Compliance and risk teams | Faster review, lower cost, stronger controls |
| AI-powered lending | Decision-engine | Alternative data expands credit access | Thin-file borrowers and BNPL users | Improves risk models and inclusion potential |
| Smarter digital wallets | Customer-facing | Wallets become financial hubs, not just payment tools | Mobile-first consumers | Whoever owns the wallet owns the relationship |
| Data trust and AI governance | Governance-trust | Explainability and data rights become competitive | All fintech operators | Trust is now a product metric, not just a legal one |
Why Is AI Accelerating Fintech in 2026?
Three forces converged at the same time, and the result is what we’re seeing now.
First: financial data became more accessible. Open banking frameworks and API-based connections let fintech products read account data, payment history, and cash-flow patterns in real time. In the US, the CFPB’s Personal Financial Data Rights rule is pushing the market toward secure, consumer-authorized data sharing — eliminating riskier screen-scraping approaches CFPB Personal Financial Data Rights.
Second: cloud-native infrastructure lowered the cost of iteration. New fintech products can test and ship faster than legacy institutions. That compresses product cycles from years to weeks.
Third: AI tools got significantly better at financial workflows. Modern systems can detect anomalies, score credit risk, summarize transactions, and support decisions in seconds — not days.
The result: the economics of financial innovation have shifted permanently. A lender can assess a borrower faster. A fraud system can flag a suspicious transfer before a human analyst even opens the case. A neobank can personalize a savings nudge at exactly the right moment.
The most important fintech trends in 2026 aren’t new interfaces. They’re better decision systems.
The 7 Top Fintech Trends in 2026
1. How Is Hyper-Personalized Banking Changing Financial Services?
Banking used to be reactive. You checked your balance. You saw what you already spent. You got a generic email.
Now it’s predictive. The best financial apps warn you about overdraft risk before it happens, suggest a transfer when your savings dip, and tailor offers based on actual behavior — not demographic segments.
This is what “AI in finance” feels like to a real user. The value isn’t the AI itself. It’s the timing. The right insight, delivered before the problem gets worse, is worth far more than a feature list.
What changed in 2026: Personalization shifted from a marketing tool to a core product capability. Banks that understand user behavior faster reduce churn and deepen account usage — without increasing headcount.
Operator takeaway: Generic notifications are now a competitive disadvantage. The question isn’t whether to personalize. It’s whether your personalization is useful or just noise.
See AI in digital banking for a deeper consumer-facing breakdown.
2. What Is Embedded Finance and Why Does It Matter in 2026?
Embedded finance is one of the most structurally important fintech shifts happening right now.
Financial products — payments, lending, insurance, savings — are appearing inside retail apps, SaaS platforms, payroll systems, marketplaces, and mobility tools. Users don’t need to visit a bank. The financial product comes to them.
AI makes this possible at scale. It enables real-time identity checks, fraud screening, pricing logic, eligibility decisions, and personalization — all running behind the platform’s native experience.
The deeper implication: The financial product still exists. But the customer relationship may belong to the platform, not the bank. Whoever controls the experience controls the data. Whoever controls the data controls the future offer.
What changed in 2026: Embedded finance matured from a novelty into a core distribution channel. For banks that build or supply embedded products, this is a growth engine. For those that don’t, it’s a disintermediation risk.
3. How Is AI Changing Fraud Detection in Finance?
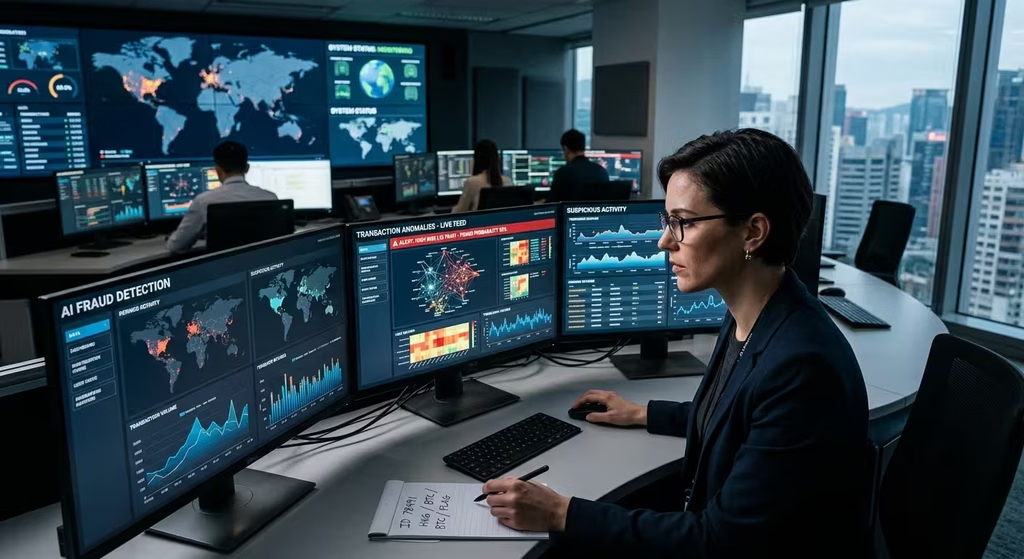
Fraud prevention is one of AI’s most mature applications in fintech — and one of its most urgent.
The FTC reported that consumers lost more than $10 billion to fraud in 2023, a first-time milestone that marked a 14% rise over 2022 FTC 2023 Fraud Losses. That number almost certainly climbed further in 2024 and 2025.
Old fraud systems relied on fixed rules: flag anything over $500 in a new city, or two charges in two minutes. Criminals figured those rules out. Now they mimic normal behavior for weeks before acting.
Modern AI fraud detection works differently. It builds a behavioral baseline for every account — your regular merchants, typical transfer amounts, usual devices. When something deviates, even slightly, the system scores the risk and responds in milliseconds.
The part most fintech articles miss: Some of the hardest fraud cases in 2026 involve no hacking at all. A scammer convinces a real customer to approve a transfer voluntarily. The account was never compromised. The customer clicked send. No privacy setting stops that. It requires product design, user education, and behavioral safeguards built into the experience itself.
What changed in 2026: Fraud systems moved from rule-based to behavior-based. The gap between the two is significant: modern systems catch patterns that static rules never could.
For a full breakdown, see AI fraud detection in finance and AI financial data privacy risks.
4. What Is Regtech and How Is AI Transforming Compliance?
Compliance is one of the least glamorous parts of fintech. It’s also one of the most important.
AI compliance tools — broadly called regtech — now handle:
- transaction monitoring
- KYC (Know Your Customer) identity review
- AML (Anti-Money Laundering) screening
- document analysis
- anomaly investigation
- regulatory reporting
The business case is straightforward: if compliance teams can delegate low-value review work to AI systems, they can focus human attention on edge cases that actually require judgment.
The regulatory context: The EU AI Act classifies certain AI systems used in credit scoring and financial decisions as “high-risk,” requiring human oversight, explainability, and ongoing monitoring EU AI Act. In the US, the NIST AI Risk Management Framework gives institutions a voluntary but influential governance model NIST AI RMF.
What changed in 2026: Fintech AI compliance moved from a separate concern into product design. Building explainability and oversight into AI systems from the start is now a requirement — not a retrofit.
Operator takeaway: Compliance is no longer a cost center you optimize after launch. It’s a design constraint that shapes what you can build and how fast you can scale.
5. How Is AI Expanding Access to Credit and Lending?
Traditional credit models have a structural problem. They work well for people with thick credit files, long histories, and W-2 income. They fail almost everyone else.
About 32 million Americans have no credit score at all. They may pay rent on time, have stable income, and handle money carefully — but none of that shows up in a FICO score. AI-powered lending systems can fill that gap by using alternative data: cash-flow patterns, payment behavior, income stability, and account history.
This creates the possibility of better risk assessment and broader credit access — but only if the data, models, and monitoring are well-designed. AI can widen access. It can also encode bias if built carelessly.
BNPL as a live example: Real-time buy-now-pay-later approvals often use machine learning models to assess creditworthiness in under two seconds, without a traditional credit check. For a detailed look at how that works, see BNPL and AI risk assessment.
What changed in 2026: AI lending moved from pilot programs to mainstream infrastructure. The question for operators is no longer whether to use AI in lending — it’s whether your models are fair, explainable, and compliant.
6. Why Are Digital Wallets Becoming More Important Than Bank Accounts?
Digital wallets started as payment shortcuts. They’ve become financial command centers.
Today’s wallets handle payments, peer-to-peer transfers, stored credentials, rewards, budgeting prompts, embedded lending, and savings features — all in one interface. They sit closer to the customer’s daily life than most bank apps.
And whoever controls that daily interface tends to control the relationship.
The CFPB’s data-rights work is relevant here. As consumers increasingly expect to move financial data between apps and platforms, the wallet becomes the central hub for that movement CFPB data rights rulemaking.
The strategic reality: Whoever owns the wallet often owns the attention. The bank that issued the card may be invisible. The platform where the payment happens is not.
What changed in 2026: Wallets became financial interfaces, not just payment tools. That shift matters for every institution that still thinks of payments as a standalone product.
7. Why Are Data Trust and AI Governance Now Competitive Advantages?
Speed is not enough. Trust is the new differentiator.
Users are getting sharper about what apps can access, how their data gets used, and what happens when AI gets something wrong. Regulators are moving in the same direction. And the products that win long-term will be the ones that handle both well.
The new competitive questions:
- Can you explain an AI-driven decision in plain language?
- Do you use read-only secure access instead of asking for login credentials?
- Can users easily revoke permissions?
- Do you have auditable oversight built into your AI systems?
These used to be legal department questions. Now they directly affect adoption, retention, and brand trust.
What changed in 2026: Data governance and explainability became product attributes — not compliance checkboxes. Users notice. Regulators notice more.
For a practical look at what this means for connected financial apps, read AI financial data privacy.
What Is AI Actually Changing About Fintech in Practice?
Here’s the distinction most coverage misses:
Visible changes (what users notice):
- faster dispute resolution
- better fraud alerts
- smarter spending summaries
- quicker loan approvals
- more relevant product offers
Invisible changes (what runs underneath):
- behavioral risk scoring
- payment routing optimization
- document verification
- model-based credit pricing
- compliance triage and anomaly detection
A customer may never interact with the AI directly. But they feel when it works: the card clears, the fraud gets caught, the approval comes through in seconds, the offer arrives at exactly the right moment.
The core insight: AI in fintech is not primarily a user-experience story. It’s a decision-quality story. Better decisions, made faster, at scale — that’s the real competitive advantage.
What Do Most Fintech Trend Articles Get Wrong?
Most roundups stop at “AI is growing.” That doesn’t help anyone. Here are the gaps worth naming.
Speed is not the same as trustworthiness
A fast AI system that makes unfair or opaque decisions creates regulatory and reputational risk. Speed and explainability have to move together.
Better underwriting ≠ fairer underwriting
AI can widen credit access — but only if the training data, governance, and monitoring are strong. The model doesn’t automatically fix bias. It can also encode it at scale.
The hardest fraud in 2026 doesn’t involve hacking
Authorized push payment fraud — where a real customer approves a manipulated transfer — is one of the fastest-growing scam types. It bypasses every technical control because the user clicked send. Solving it requires education, UX design, and behavioral safeguards, not just detection systems.
The most valuable fintech AI is usually invisible
The highest-impact use cases are often in compliance, operations, and risk — not in customer-facing features. That’s where the economics are most compelling.
The future is hybrid, not winner-take-all
Banks are not disappearing. Fintechs are not replacing every incumbent. The market is layering: banks supply infrastructure, fintechs build experience, platforms embed products, and AI connects the decision logic across all of it. No single player owns the whole stack.
How Should You Evaluate a Fintech AI Claim?
Whether you’re a consumer comparing apps or an operator evaluating vendors, ask these five questions:
- What specific workflow is AI improving?
Fraud detection, credit scoring, compliance review, personalization, payments — or just a chatbot?- What data is the system actually using?
Transaction history, behavioral signals, document data, cash-flow patterns — and is that data access secure and limited?- Is the benefit measurable?
Faster approvals, fewer false positives, lower loss rates, better recovery times — or just a marketing claim?- What human oversight exists?
Responsible AI financial systems have review paths, override capabilities, and accountability structures built in.- What rights and protections still apply?
In credit, data sharing, and financial decisions, official guidance matters. Start with CFPB consumer data rights, FDIC deposit insurance FAQs, and the NIST AI Risk Management Framework.
What Do the 2026 Fintech Trends Mean for Operators?
If you build, sell, or manage fintech products, the practical implications are clear:
- Personalization must be useful and timely — not just present.
- Fraud systems must adapt continuously, not just at launch.
- Lending models need explainability built in, not bolted on.
- Data access and consent must be transparent and easy to revoke.
- AI governance is now a product design issue, not only a legal one.
- Trust signals — clear policies, secure connections, audit trails — matter more than feature lists.
The firms that win this cycle won’t just ship new capabilities. They’ll prove those capabilities are accurate, fair, auditable, and trustworthy.
Frequently Asked Questions
What are the top fintech trends in 2026?
The top fintech trends in 2026 are hyper-personalized banking, embedded finance, AI fraud detection, regtech and compliance automation, AI-powered lending, smarter digital wallets, and stronger data governance. These trends span three layers: customer-facing experience, back-end decision intelligence, and governance and trust.
How is AI changing the fintech industry?
AI is changing fintech by improving the quality, speed, and scale of financial decisions — in fraud detection, credit assessment, compliance review, personalization, and payment processing. The most important changes are often invisible to users but felt in faster approvals, better fraud catches, and more relevant products.
Why is AI important in fintech?
AI helps fintech firms process large volumes of financial data, detect patterns that rule-based systems miss, reduce manual workload, and serve customers more precisely. It also enables new business models — like real-time BNPL underwriting — that weren’t practical with older technology.
What are the most common AI applications in financial services?
Common AI applications in financial services include fraud detection, credit scoring, underwriting, KYC and AML monitoring, document verification, customer support automation, cash-flow analysis, and personalized financial guidance.
What is the future of fintech and banking?
The future of fintech and banking is more connected, more intelligence-led, and more layered. Banks, fintechs, platforms, and AI systems will increasingly share the financial services value chain rather than compete in separate lanes. The institutions that combine strong AI capability with clear governance and user trust will hold the strongest position.
Are neobanks safe to use in 2026?
Many neobanks partner with FDIC-insured institutions, which means your deposits may carry standard protections. However, users should verify the specific partner bank and account structure. The FDIC explains that deposit insurance generally covers up to $250,000 per depositor, per insured bank, per ownership category FDIC deposit insurance FAQ. Always confirm before depositing.
What is open banking and why does it matter?
Open banking refers to consumer-authorized financial data sharing through secure, standardized APIs — rather than screen scraping or credential sharing. It matters because it enables better financial apps, more competition, and greater consumer control over their own data. The CFPB’s data rights rulemaking is the relevant US framework CFPB data rights rulemaking.
What is the biggest risk in fintech AI right now?
One of the biggest underreported risks is authorized fraud — where real customers are manipulated into approving bad transactions. Technical controls can’t stop it because the user took the action voluntarily. Solving it requires product design, behavioral education, and proactive safeguards built into the experience. For a deeper look, see AI financial data privacy risks.
Bottom Line: What the 2026 Fintech Trends Actually Mean
Here’s the short version: fintech in 2026 is not primarily a story about new products. It’s a story about better decision systems — and who builds them well.
AI is improving the logic underneath every major financial workflow: how risk gets scored, how fraud gets flagged, how compliance gets reviewed, how credit gets extended, how data gets protected. The customer usually doesn’t see the model. They feel the result.
The firms that stand out won’t just move faster. They’ll build systems that are more accurate, more explainable, and more trustworthy — and they’ll be able to prove it.
That’s the real differentiator in 2026. Not the AI feature. The AI foundation.
For deeper coverage of the trends driving this shift:
- AI in digital banking
- BNPL and AI risk assessment
- AI fraud detection in finance
- AI financial data privacy
Fintech · Editorial Integrity
Sources & Citations
Public frameworks, regulatory guidance, and current reporting behind this guide to the biggest fintech trends of 2026 — covering AI in banking, embedded finance, fraud detection, regtech, lending, digital wallets, and governance.
This guide is grounded in public regulatory frameworks, government reporting, and current industry documentation covering the major forces shaping fintech in 2026. We prioritized official sources for data rights, AI governance, fraud loss reporting, and banking protections, then used them to frame the broader market trends discussed in the article. Because fintech regulation, product capabilities, and market behavior evolve quickly, readers should verify the latest rules, vendor claims, and institutional disclosures before making financial or operational decisions.
View full sources, methodology, and editorial notes
This article was developed using primary regulatory materials, government guidance, and named institutional frameworks relevant to fintech in 2026. We favor official policy sources, agency reporting, and recognized standards when explaining open banking, AI governance, fraud risk, compliance expectations, and deposit protections. Supporting article references are included where they extend a topic discussed in the guide. This article is educational information and should not be treated as legal, financial, compliance, or investment advice.
- Consumer-authorized financial data sharing and open banking: CFPB — Personal Financial Data Rights — cited for the article’s explanation of secure consumer-authorized data access, open banking direction, and the shift away from riskier screen-scraping methods.
- Fraud loss reporting and scam trends: FTC — Nationwide Fraud Losses Top $10 Billion in 2023 — cited for the benchmark showing the scale of consumer fraud losses and why AI-driven fraud detection remains a major fintech priority.
- AI governance and risk management framework: NIST — AI Risk Management Framework — cited for the governance principles referenced in the article’s discussion of oversight, explainability, and trustworthy AI deployment in financial services.
- European rules for high-risk AI systems: EU AI Act — cited for the regulatory context around AI systems used in credit, financial decisions, and compliance-sensitive workflows.
- Deposit protection and bank account safety context: FDIC — Deposit Insurance FAQ — cited for the article’s explanation of deposit insurance protections relevant to neobanks and partner-bank account structures.
- AI in digital banking: Tech Capital Hub — AI in Digital Banking — cited as a related internal reference for the customer-facing side of AI-driven personalization and banking experience design.
- AI-powered underwriting and BNPL decisioning: Tech Capital Hub — BNPL and AI Risk Assessment — cited as a supporting internal source for the section on AI lending, real-time approvals, and alternative risk models.
- Behavior-based fraud detection in finance: Tech Capital Hub — AI Fraud Detection in Finance — cited as a supporting internal source for the article’s discussion of behavior-based fraud models and modern payment risk controls.
- AI data rights, permissions, and privacy risk: Tech Capital Hub — AI Financial Data Privacy — cited as a supporting internal source for the governance, permissions, and trust issues discussed throughout the guide.
Fintech Trends 2026 · Editorial Standards
Our Editorial Standards
Tech Capital Hub applies Google’s E-E-A-T framework to every fintech and AI analysis piece, emphasizing practical clarity, public documentation, and verifiable institutional sources over hype. This guide draws on trusted frameworks and reporting where they support specific claims — including CFPB materials for consumer-authorized financial data sharing, FTC reporting for fraud loss context, the NIST AI Risk Management Framework for governance, the EU AI Act for high-risk AI oversight, and FDIC guidance for deposit protection context. Where adoption patterns, product behavior, or market outcomes are still evolving, we describe the direction of change carefully rather than overstate certainty.
View how our editorial standards apply to this article
Written for Operators, Not Trend Chasers
This article is structured for readers who need practical meaning, not just headlines. Instead of listing buzzwords, it explains how AI changes real workflows across banking, payments, lending, fraud, compliance, and customer experience. The goal is to help founders, operators, and finance leaders understand what these shifts mean in day-to-day execution, not just in theory.
Complex Fintech Systems Explained in Plain Language
The guide breaks down difficult topics — like embedded finance, behavior-based fraud detection, AI lending models, digital wallet power, and governance risk — into language that stays precise without becoming overly technical. It also separates visible product changes from the invisible decision systems underneath them so readers can understand where the real strategic shift is happening.
Primary Frameworks and Named Sources Over Vague Claims
Specific claims are anchored to recognized public sources where possible. Open banking and data-rights context draws on CFPB guidance, fraud benchmarks reference FTC reporting, governance discussion relies on NIST and EU AI Act materials, and deposit protection references FDIC guidance. We also point to supporting internal analysis only where it meaningfully extends the topic already introduced in the article.
Clear About Uncertainty, Risk, and Limits
Fintech changes quickly, and responsible coverage should acknowledge that. This guide avoids promising outcomes, avoids treating vendor claims as proof, and distinguishes regulatory direction from settled global consensus. It is educational analysis, not legal, compliance, investment, or financial advice. Corrections, source questions, or factual challenges can be sent to the editorial team for review.
Fintech · About the Author
James Whitfield
Senior Fintech Editor & Analyst · Tech Capital Hub
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering where financial technology, AI, and real business outcomes meet. In this guide, he breaks down the biggest fintech trends of 2026 in plain language — from hyper-personalized banking and embedded finance to AI fraud detection, digital wallets, lending, and governance.
View full author bio, credentials, and links
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering where financial technology, AI, and real business outcomes meet. He writes for founders, operators, and finance leaders who need to understand what a tool, workflow, or regulatory shift actually means once it leaves the pitch deck and enters day-to-day use.
His reporting focuses on the practical side of fintech: how AI-driven forecasting tools handle messy real-world inputs, how digital banking platforms evolve, how lending models behave under live conditions, and how fraud detection, payment infrastructure, compliance, and governance are changing across the industry. For this article, James maps the 2026 fintech landscape around the decision systems quietly reshaping banking, payments, lending, risk, and trust. He separates what users see from the infrastructure running beneath it, and he evaluates trends based on utility, oversight, and measurable business impact rather than industry hype. All articles are educational information and should not be treated as financial, legal, compliance, or investment advice.
- Covers fintech through the lens of real-world business impact, not surface-level trend reporting
- Explains AI-driven shifts across banking, payments, compliance, lending, wallets, and fraud detection in plain language
- Tracks how financial tools perform after launch, including risk controls, governance pressures, and operational trade-offs
- Focuses on separating genuine innovation from hype using technical, regulatory, and business-outcome lenses
- Grounds analysis in public frameworks, named reporting, and clear editorial standards with educational framing
Enjoying our content?
Click below to add us as a preferred source. Google will prioritize our latest articles in your Top Stories, AI Mode, and AI Overviews.
Preferred Source on Google