AI Fraud Detection in Finance: How It Works, What It Catches, and Why It Matters
Fintech Analyst & Founder · Tech Capital Hub
Marcus Delray is an independent fintech and digital-risk analyst who writes about how artificial intelligence, fraud, online scams, payment systems, and modern financial technology intersect in the real world. In this guide, he breaks down how AI fraud detection works in real time, what it catches, from fraud rings and deepfakes to forged documents and friendly fraud, and why explainability now matters as much as accuracy.
Here’s something that surprised me when I first started covering financial fraud. Many of the costliest fraudsters aren’t hackers at all. They’re ordinary customers who buy something, receive it, and then dispute the charge anyway.
That’s one reason AI fraud detection in finance has become so important. It helps banks, fintechs, and merchants spot suspicious activity before the money moves. It also catches threats that older systems were never built to see.
This guide walks you through how AI fraud detection works, what it catches, and what to look for in a tool. You’ll also see why explainability now matters as much as accuracy. Want the bigger picture first? Explore our guide to Fintech Trends 2026. You can also dive deeper into AI financial data privacy and the BNPL and AI risk assessment for more on how AI is reshaping financial services.
Quick answer: AI fraud detection in finance uses machine learning, anomaly detection, behavioral biometrics, graph analysis, and document intelligence to spot suspicious activity in real time. It scores each transaction against a customer’s normal behavior. It then approves, challenges, or escalates each transaction before funds clear.
Table of Contents
Why AI Fraud Detection in Finance Matters More Than Ever
AI fraud detection matters because fraud now moves faster, spans more channels, and costs far more than the original loss.
Fraud isn’t just growing. It’s changing shape!
Criminals now use generative AI, stolen identities, and networks of linked accounts. At the same time, disputes from real customers keep climbing. Both trends hit the bottom line hard.
Here’s the eye-opening part. LexisNexis Risk Solutions’ True Cost of Fraud research has found that every $1 lost to fraud can cost U.S. financial services firms more than $4. That figure includes fees, labor, recovery, and other hidden costs.
So a $50 problem rarely costs just $50. For subscription services, digital wallets, and buy now, pay later (BNPL) platforms, those costs can stack up fast.
Speed matters too. Instant payment rails move money in seconds. The Federal Reserve’s FedNow resources on instant payments note that fraud prevention functions must run in real time. If a system takes 30 minutes to flag a threat, the funds may already be gone.
That’s why AI fraud detection in finance has moved from “nice upgrade” to core infrastructure. It works at the speed money now moves.
Recap: Fraud is faster, smarter, and more costly, so detection has to keep pace.
How Real-Time Transaction Monitoring Works
Real-time transaction monitoring scores each payment against dozens of risk signals in milliseconds, before it clears.
So how does a bank know, in about two seconds, that a charge looks wrong? AI transaction monitoring follows three clear steps.
Step 1: Data Collection
The system gathers signals from several sources at once:
- Transaction data: amount, merchant type, location, and time of day
- Device data: browser fingerprint, IP address, and login patterns
- External data: breach databases and shared fraud intelligence feeds
Step 2: Baseline Building
Every account gets a behavioral profile. It isn’t a dusty snapshot from months ago. It updates after each transaction, so it reflects how you actually spend today.
Step 3: Risk Scoring
Each new transaction is compared to that baseline in milliseconds. The system then assigns a risk score.
A high score doesn’t always mean a hard block. That would frustrate good customers! Instead, well-designed systems use step-up authentication. That’s an extra check triggered only when risk is high, such as a one-time code or a quick face scan.
Real customers breeze right through. Fraudsters get stopped cold.
What This Looks Like at Scale
Large banks run this process across millions of transactions every day. JPMorganChase, for example, highlights its AI and machine learning investments across operations and fraud in its 2025 Investor Day materials. Examples like this show how payment fraud detection AI can scale without endless manual review.
Recap: Real-time monitoring collects signals, compares them to a living baseline, and responds before money moves.
Why Machine Learning Fraud Prevention Beats Rule-Based Systems
Machine learning fraud prevention outperforms rules because it learns each customer’s normal behavior and adapts as fraud tactics change.
Rule-based systems were the industry standard for years. They follow simple logic. Flag any purchase over $500 in a new city. Flag two charges within two minutes.
That sounds sensible. But criminals learned these rules long ago.
Here’s how they slip past them:
- They test stolen cards with tiny purchases, like $1.99.
- They mimic normal behavior for weeks before making a big move.
- They use AI-generated video to pass identity checks during sign-up.
Meanwhile, rigid rules create a flood of false alarms. Legacy systems often generate far more false alerts than real fraud cases. Analysts spend hours clearing harmless alerts while real fraud slips through.
That’s not just a staffing issue. It’s an architecture issue.
Machine learning fraud prevention works differently. It doesn’t check transactions against a fixed list. It learns what “normal” looks like for each account, such as your usual spending hours, home city, and devices.
A charge gets flagged because it doesn’t look like you. Not because it broke a generic rule.
Here’s a simple side-by-side comparison:
| Feature | Rule-Based Systems | Machine Learning Systems |
|---|---|---|
| How it decides | Fixed “if-then” rules | Learned behavior patterns |
| Adapts to new tactics | Only after manual updates | Continuously |
| False positives | Often high | Typically lower when well-tuned |
| Personalization | Same rules for everyone | Unique baseline per account |
Recap: Machine learning adapts as fraud evolves, while static rules fall behind.
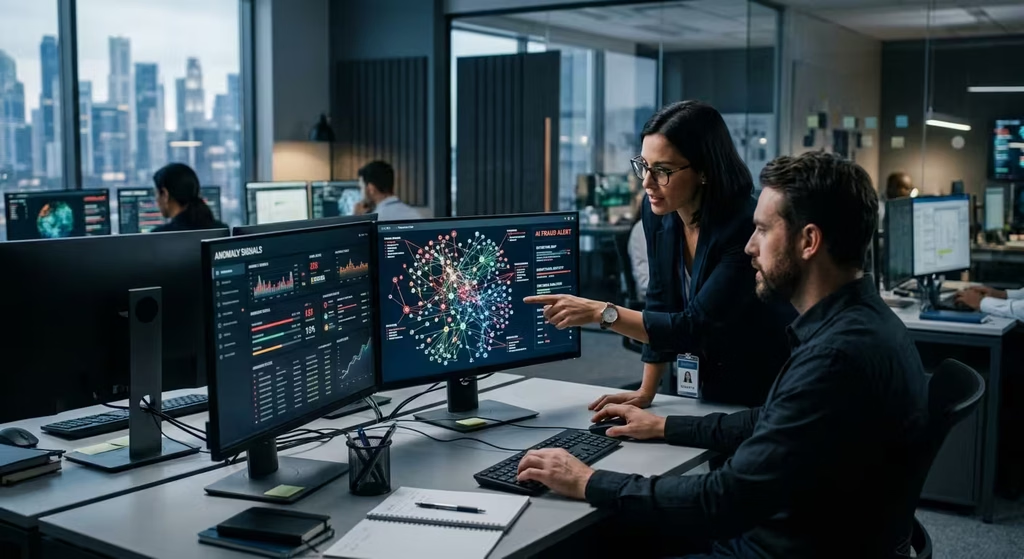
How AI Detects Anomalies, Fraud Rings, and Identity Abuse
Anomaly detection in finance is the engine behind most modern fraud tools. It spots activity that doesn’t match an expected pattern.
But different fraud types need different methods. Three technologies do much of the heavy lifting.
Graph Neural Networks and Fraud Rings
Graph neural networks detect fraud rings by mapping hidden links between accounts, devices, and transfers.
Most tools look at one transaction at a time. That works for obvious cases. But fraud rings don’t operate through single transactions.
They use shared devices, shell companies, and chains of mule accounts. A mule account is an account used to move stolen money, sometimes by people who don’t realize what’s happening.
A graph neural network (GNN) looks at relationships, not just individual charges. Picture a giant web. Each account is a point. Each link between accounts is a connection, like a shared device, phone number, or pattern of small transfers.
When several clean-looking accounts behave the same suspicious way, the GNN spots the ring. That’s true even when each account looks perfectly fine on its own!
Thoughtworks offers a clear, practical overview of graph neural networks in fraud prevention, including how they surface networked fraud that rules often miss.
Behavioral Biometrics and Account Takeover
Behavioral biometrics stop account takeover by checking whether a user behaves like the real account holder, not just whether they know the password.
Account takeover and synthetic identity fraud share one goal. The attacker has to look like you.
- Account takeover means a criminal gains control of a real customer’s account.
- Synthetic identity fraud blends real and fake details to create a new, believable person.
Stealing a password used to be enough. Now, attackers may submit deepfake video to pass a liveness check during sign-up. A liveness check confirms that a real, live person is in front of the camera, not a photo, mask, or recording. Generative AI has made faking that check easier than most people realize.
That’s why modern tools layer two kinds of defense.
Behavioral biometrics track how you interact with a device:
- Typing rhythm and speed
- Mouse movement and pointer paths
- Scrolling and swiping habits
Liveness and deepfake detection analyze the video itself:
- Tiny shifts in skin texture
- How light reflects off a face, frame by frame
Together, these signals catch impostors no human reviewer could spot. For neobanks, BNPL apps, and digital wallets, this protection is vital. Fraud during a growth phase is especially painful. More volume means more damage, fast.
Document AI and Forged Financial Records
Document AI catches forged financial records by analyzing a file’s hidden metadata, not just the words on the page.
Here’s something most people outside compliance don’t know. Submitted documents are a common entry point for fraud. Think forged bank statements or fake proof-of-income letters.
A skilled forgery can fool a human reviewer. Document AI doesn’t just read the text. It examines the file’s metadata, the digital fingerprints left by the software that created or edited it.
For example, some document AI tools can flag when a PDF was saved through photo-editing software that the issuing bank never uses. It’s not catching a typo. It’s catching the tool behind the forgery.
Best of all, this check can run automatically at sign-up. Not months later in a manual audit.
Recap: Graphs catch rings, biometrics and liveness checks catch impostors, and document AI catches forgeries.
How AI Helps Prevent Chargebacks and Friendly Fraud
AI helps prevent chargebacks by spotting dispute risk early and helping merchants respond with stronger evidence.
A chargeback is a forced reversal of a card payment, initiated by the cardholder’s bank. Ask most people what drives them, and they’ll say hackers. Stolen cards. Hijacked accounts.
But there’s a quieter culprit: friendly fraud.
What is friendly fraud? Friendly fraud happens when a real cardholder makes a real purchase and then disputes it anyway. Sometimes it’s confusion. Sometimes it’s intentional. Industry estimates suggest it now drives a large share of chargebacks, often a majority.
The math is tough on merchants. A $5 dispute can cost nearly as much to handle as a $500 one. Fixed fees can exceed the value of small transactions. Card networks also run monitoring programs that can bring extra fees for merchants with high dispute rates.
So many businesses simply write off small disputes. Unfortunately, that can teach customers that disputing works.
Industry research, including work from Chargebacks911, suggests customers who receive an undeserved refund are more likely to dispute again. That creates a cycle often called the chargeback flywheel. Each bad dispute can feed the next one.
How Chargeback Prevention AI Works
Chargeback prevention AI works at two levels:
- Early warning signals. Real-time monitoring can spot risky behavior before a dispute is filed. Examples include repeated visits to the refund policy or unusual support contact. The business can then reach out first.
- Dispute intelligence. AI tools help merchants gather evidence and respond quickly. Fast, well-documented responses tend to win more disputes.
Helpful tip: Pair AI alerts with clear billing descriptors and easy cancellation flows. Many disputes start when customers don’t recognize a charge or can’t cancel easily. Fixing those friction points is one of the simplest and most effective forms of friendly fraud prevention!
Recap: Friendly fraud is costly and self-reinforcing, but AI can break the cycle early.
What Businesses Should Look for in AI Fraud Detection Tools
The best AI fraud detection tools score in real time, explain their decisions, and cover payments, identity, and disputes in one view.
Choosing a tool can feel overwhelming. The good news? You don’t need to be a major bank to benefit.
Today, many fraud detection tools for small businesses connect to checkout flows through simple APIs or platform apps. Pricing often scales with transaction volume. A few commonly cited examples include:
- SEON: known for device fingerprinting and digital footprint checks in eCommerce
- Sift: known for real-time decisioning backed by a global fraud data network
- Feedzai: known for explainable risk decisions in banking
Running a Shopify store doing $30,000 a month? This is worth exploring now, before a fraud spike forces your hand.
Your AI Fraud Tool Checklist
Use these questions when you compare vendors:
- Real-time scoring: Does it score transactions in milliseconds, not minutes?
- Smart responses: Can it trigger step-up authentication instead of blocking good customers?
- Unified coverage: Does it handle payments, identity, and account activity together?
- Explainability: Can it show why a transaction was flagged?
- Human review options: Can your team escalate and override decisions easily?
- Easy integration: Does it plug into your current payment stack?
- Chargeback support: Does it help with dispute evidence and early warnings?
Common Mistake: Too Many Disconnected Tools
Many businesses run separate systems for card fraud, anti-money laundering (AML), and identity checks. Each one scores the same customer on its own. The result is coverage gaps, duplicate alerts, and a lot of noise.
The fix is consolidation. More teams are moving to FRAML (fraud and anti-money laundering) platforms, which combine both kinds of monitoring. Many follow a “one customer, one alert” approach. Vendors report this can meaningfully reduce false positives.
Keep Humans in the Loop
AI doesn’t replace fraud teams. It changes their work.
At large banks such as JPMorganChase, automation has helped shift staff from routine alert processing toward complex investigations and client-facing roles. That hybrid model works best. Pure automation struggles with edge cases. Pure manual review can’t scale.
Recap: Look for speed, unified coverage, explainability, and a clear role for human reviewers.
Why Explainable AI Matters in Fraud Detection Compliance
Explainable AI matters because regulators increasingly expect financial institutions to show why an AI system made a decision.
Accuracy alone isn’t enough anymore.
Explainable AI fraud detection means the system can show which factors drove a risk score. That helps teams review decisions, answer customer questions, and spot bias early.
Here’s how the regulatory picture is shaping up.
The EU AI Act
The EU AI Act (Regulation (EU) 2024/1689) lists AI used for creditworthiness assessment and credit scoring as “high-risk” in Annex III. These systems face requirements for human oversight, transparency, and risk management.
Notably, that same Annex III entry excludes AI systems used to detect financial fraud. However, many tools blend fraud scoring with credit or onboarding decisions. Those combined uses may still fall under stricter rules. Implementation timelines may also shift under proposed EU amendments, so track updates closely.
US Rules and Data Rights
In the US, the CFPB finalized its Personal Financial Data Rights Rule under Section 1033 in 2024. According to the CFPB’s executive summary of the rule, covered providers must share consumer data through secure interfaces at the customer’s request. The rule aims to reduce reliance on risky screen scraping. It has since faced reconsideration and legal challenges, so check its current status before relying on specific dates.
The Homebuyers Privacy Protection Act, which took effect in March 2026, limits how credit report data tied to mortgage inquiries can be shared for marketing. It reflects growing attention on how consumer credit data gets used.
At the state level, laws on unfair or deceptive practices may also apply to AI-driven lending decisions. As of October 2026, federal proposals to limit state AI regulation have surfaced, but state rules remain an active factor.
What This Means in Practice
Any AI touching credit decisions, fraud scoring, or identity checks should be explainable. A black-box model that works but can’t explain itself can create real compliance risk.
Recap: Build explainability and human oversight in from day one, not as an afterthought.
Key takeaway: Fraud is happening right now, at scale. The businesses that win will see it before the money moves. Start by auditing your current fraud stack against the checklist above, then close your biggest gap first!
People Also Ask
These quick answers cover the questions people ask most about AI fraud detection in finance.
What is AI fraud detection in finance?
AI fraud detection in finance uses machine learning and behavioral analysis to spot suspicious transactions, identity abuse, forged documents, and chargeback risk in real time.
How do banks use AI to detect credit card fraud in real time?
Banks build a behavioral profile for each account. New transactions are scored against it in milliseconds. The system then approves the charge, requests extra verification, or escalates it for review.
How does anomaly detection work in finance?
Anomaly detection learns normal behavior for each account. New activity is compared to that baseline. Unusual activity gets a higher risk score, which guides the next step.
What is the difference between friendly fraud and true fraud?
True fraud involves unauthorized use, such as stolen cards or account takeover. Friendly fraud happens when the real account holder disputes a legitimate charge.
Can small businesses use AI fraud detection tools?
Yes. Many fraud detection tools for small businesses plug into checkout through an API or a platform app. Pricing often scales with transaction volume.
Does the law require AI fraud detection?
No single law requires it. However, rules like the EU AI Act set requirements for certain AI uses in finance, such as credit scoring. US data and consumer protection rules may also apply.
Is AI fraud detection high-risk under the EU AI Act?
Usually not when used solely for fraud detection. The Act excludes fraud detection from its credit-scoring high-risk category. Tools that also support credit decisions may still be high-risk.
Why does explainable AI matter in fraud detection?
Explainable AI shows why a decision was made. That supports compliance, customer trust, and fair outcomes.
AI Fraud Detection & Financial Risk · Editorial Integrity
Sources & Citations
The public fraud data, AI governance frameworks, identity standards, and payment security guidance behind this guide. It covers real-time transaction monitoring, machine learning fraud prevention, fraud rings, deepfakes, chargebacks, and explainable AI compliance.
Fraud moves fast, so we built this guide on sources you can actually trust. We leaned on public fraud reporting, AI governance frameworks, digital identity standards, and payment security guidance to explain how AI flags suspicious transactions in milliseconds. You’ll also see how machine learning outperforms rigid rules and how connected-account analysis uncovers fraud rings. Plus, we cover why deepfakes and forged documents are raising the stakes, and why regulators now expect fraud decisions to be explainable. Quick tip: fraud tactics, vendor features, and compliance rules keep changing, so check the latest official guidance before you make security, vendor, or compliance decisions.
View full sources, methodology, and editorial notes
We developed this article using government fraud data, regulatory and supervisory materials, recognized technical standards, and related Tech Capital Hub research. Official guidance and established frameworks come first when we explain real-time transaction monitoring, anomaly detection, identity verification, synthetic identity and deepfake risk, document fraud, chargeback and friendly fraud prevention, and model explainability. Supporting internal references add context on financial data privacy and wider fintech trends. This article is general educational information and does not constitute legal, financial, compliance, or investment advice.
- Consumer fraud trends and reported losses: FTC — Consumer Sentinel Network — referenced for context on how fraud reports and losses are tracked in the US, and why financial institutions are investing in faster, smarter detection.
- Financial crime, suspicious activity, and deepfake threats: FinCEN — Financial Crimes Enforcement Network — referenced for the article’s discussion of suspicious activity monitoring, emerging fraud typologies, and the growing use of synthetic media in identity abuse.
- AI governance, explainability, and model oversight: NIST — AI Risk Management Framework — referenced for the sections on explainable AI, auditability, bias monitoring, and responsible oversight of automated fraud decisions.
- Model risk management in financial services: Federal Reserve — SR 11-7 Guidance on Model Risk Management — referenced for the article’s explanation of why banks and fintechs must validate, document, and monitor the machine learning models behind fraud scoring.
- Digital identity verification and authentication: NIST — Digital Identity Guidelines (SP 800-63) — referenced for context on identity proofing, authentication strength, and the verification signals AI uses to spot account takeover, forged documents, and impersonation.
- Payment data security standards: PCI Security Standards Council — referenced for the article’s discussion of card payment security, transaction data protection, and the baseline controls that support real-time fraud monitoring.
- International AI regulation and high-risk systems: European Commission — Regulatory Framework for AI — referenced for global compliance context and growing expectations for transparency, human oversight, and documentation in AI-driven financial systems.
- Financial data access, permissions, and privacy risk: Tech Capital Hub — AI Financial Data Privacy — cited as a supporting internal reference for the sections on behavioral data, customer privacy, and responsible use of transaction signals in fraud models.
- Broader fintech and digital payments context: Tech Capital Hub — Fintech Trends 2026 — cited as a related internal pillar for the market shifts shaping AI fraud prevention, instant payments, and digital finance in 2026.
AI Fraud Detection & Financial Risk · Editorial Standards
Our Editorial Standards
Fraud moves in milliseconds, but good reporting on it should move with care. Tech Capital Hub applies Google’s E-E-A-T framework to every AI, fintech, and fraud prevention guide. That means practical clarity, named sources, and public documentation instead of hype. This article draws on trusted references where they support specific claims: FTC Consumer Sentinel data for fraud trends, FinCEN materials for suspicious activity and deepfake risk, the NIST AI Risk Management Framework for explainability and oversight, Federal Reserve SR 11-7 for model risk management, and NIST Digital Identity Guidelines for identity verification. Where fraud tactics, vendor capabilities, or regulatory expectations are still shifting, we describe the direction carefully and avoid overstating certainty.
See how our editorial standards shape this fraud detection guide
Written for Real Fraud and Risk Decisions
What actually happens in the split second after a card is tapped or a login attempt hits your system? This guide is written for finance teams, fraud analysts, fintech founders, and curious readers who want to see what goes on behind the approval screen. It walks through real-world moments such as a flagged payment, a suspicious account takeover, a forged pay stub, and a disputed charge. You can connect the technology to the decisions your team makes every day, with no abstract theory required.
Machine Learning Fraud Prevention, Explained Clearly
The guide turns complex fraud-detection concepts into plain language without losing technical accuracy. It explains how real-time transaction monitoring scores payments in milliseconds and how anomaly detection spots unusual behavior. It also shows how connected-account analysis uncovers fraud rings and how AI flags deepfakes and forged documents. You’ll learn where chargeback and friendly fraud prevention fits in, and where rules-based controls, human review, and false-positive management still matter.
Primary Sources and Named Frameworks Over Vendor Claims
Specific claims are grounded in recognized public and institutional references wherever possible. Fraud trend context comes from the FTC, and suspicious activity and synthetic media risks reference FinCEN. Explainability and governance draw on the NIST AI Risk Management Framework and Federal Reserve SR 11-7. Identity verification references NIST SP 800-63, payment security references the PCI Security Standards Council, and global AI rules reference the European Commission. Internal analysis only extends adjacent topics, such as financial data privacy and broader fintech trends.
Clear About Limits, Evolving Threats, and Regulatory Change
Fraud tactics, AI capabilities, and compliance expectations evolve quickly, so this guide avoids false certainty. It doesn’t claim any system catches every fraud attempt. It doesn’t treat vendor accuracy figures or marketing as proof. It also separates emerging regulatory direction from settled rules. This article is general educational information, not legal, financial, compliance, or investment advice. A helpful tip: before you choose a tool or update a fraud program, check current official guidance, request independent validation from vendors, and review your own model governance needs. You can send corrections or source questions to the editorial team anytime.
AI Fraud Detection & Financial Risk · About the Author
Marcus Delray
Fintech Analyst & Founder · Tech Capital Hub
Marcus Delray is a fintech analyst and the founder of Tech Capital Hub, with over a decade of experience researching financial technology. In this guide, he takes you behind the scenes of AI fraud detection: how it scores transactions in real time, how it uncovers fraud rings, deepfakes, and forged documents, how it helps curb chargebacks and friendly fraud, and why explainability now matters just as much as accuracy.
View full author bio, focus areas, and links
Marcus Delray is a fintech analyst and the founder of Tech Capital Hub, with over a decade of experience researching financial technology. He covers AI in finance, blockchain technology, DeFi, and business accounting tools. His goal is simple: make complex fintech topics clear and actionable for investors, entrepreneurs, and finance professionals who need to understand what a technology really does before they rely on it.
For this article, Marcus breaks down how AI fraud detection works in practice. He covers how machine learning models monitor transactions in milliseconds, how anomaly detection and connected-account analysis expose suspicious patterns and fraud rings, and how AI helps flag deepfakes and forged documents. He also explains where chargeback and friendly fraud prevention fits in. Just as important, he shows where human review, model governance, and explainable decisions still matter as compliance expectations grow. All articles are general educational information and should not be treated as legal, financial, compliance, or investment advice.
- Founder of Tech Capital Hub with over a decade of experience researching financial technology
- Covers AI in finance, blockchain technology, DeFi, and business accounting tools
- Explains real-time transaction monitoring, anomaly detection, and fraud ring analysis in plain language without oversimplifying
- Separates proven fraud prevention capabilities from vendor marketing claims using technical, regulatory, and practical lenses
- Grounds analysis in public frameworks, named sources, and clear editorial standards with educational framing
Enjoying our content?
Click below to add us as a preferred source. Google will prioritize our latest articles in your Top Stories, AI Mode, and AI Overviews.
Preferred Source on Google