
How Predictive AI Builds Your Emergency Fund Without Over drafting — Even on Irregular Income
Fintech Analyst · Founder of Tech Capital Hub
Marcus covers AI in personal finance, behavioral finance technology, and smart saving tools. In this guide, he explains how predictive AI helps people automate saving, forecast cash flow, and build emergency funds with less manual effort.
Predictive AI for savings uses your income history and bill schedule to find safe moments to move money — so your emergency fund grows without triggering overdrafts. Most savings plans don’t fail because of poor discipline. They fail because the transfer lands at the wrong moment. A $50 auto-transfer hits the same day rent clears, a $35 overdraft fee arrives, and a week of progress disappears overnight.
This timing problem hits hardest when income is irregular. Gig workers, freelancers, and hourly earners can’t rely on a paycheck landing the same day every week. Fixed transfers don’t account for that — predictive AI does. Below, we break down how cash flow forecasting works, why variable income makes the timing gap worse, a six-step setup guide for emergency fund automation, where automated saving AI still falls short, and a side-by-side scenario that makes the difference concrete.
For the bigger picture on how AI is reshaping personal finance — investing, tax planning, and wealth automation — The AI Wealth Revolution is the right starting point before diving into this piece.
At a Glance
At a Glance
Five quick truths about predictive AI saving on irregular income. Tap any point to expand.
-
Saving fails most often because of timing, not willpower. A mistimed transfer can trigger an overdraft and erase a week of progress in a single hit.
-
Predictive AI for savings builds a 7-to-30-day cash flow forecast using your income history and known bills, then only moves money during a safe window when the balance can handle it.
-
Fixed auto-transfers carry the same overdraft risk as manual saving for anyone with variable income. They run on schedule whether the balance is actually ready or not.
-
Predictive AI saving works best for gig workers, freelancers, and irregular-income earners. Round-up saving is the better fit for steady earners who want a passive, low-stakes supplement.
-
Automated saving AI is not risk-free. Forecasting accuracy depends on your data history, and sudden income gaps or bank data sync delays can still cause misfires.
Key Takeaways
- Saving fails most often because of timing, not willpower — a mistimed transfer can trigger an overdraft and erase a week of progress.
- Predictive AI for savings builds a 7-to-30-day cash flow forecast using income history and known bills, then only transfers money during a verified safe window.
- Fixed auto-transfers carry the same overdraft risk as manual saving for people with variable income, because they execute on schedule regardless of account health.
- Predictive AI saving works best for gig workers, freelancers, and irregular-income earners — round-up saving is better suited to steady earners who want a passive, low-stakes supplement.
- Automated saving AI isn’t risk-free: forecasting accuracy depends on data history, and sudden income gaps or bank data sync delays can still cause misfires.
Table of Contents
Why Does Manual Saving Fail? Timing, Not Willpower, Is the Real Culprit
Saving fails for most people because the transfer decision arrives at the wrong moment — not because they lack discipline. After rent clears, after a surprise car repair, after the balance has already dropped lower than expected: that’s when the manual transfer tends to run. By then, there’s nothing safe to move.
Picture a freelancer who schedules a $50 weekly transfer every Monday. One week, a client payment runs late. Monday’s balance is lower than expected, but the transfer executes anyway. The overdraft fee arrives. According to the Consumer Financial Protection Bureau, the average overdraft fee in the US runs around $35 — meaning a single mistimed transfer can cost more than the amount being saved.
The fix isn’t more discipline. It’s a system that closes the forecasting gap before money moves.
What Does Predictive AI Actually Do Before Moving Your Money?
Predictive AI for savings analyzes your income timing, recurring bills, and spending patterns to build a short-term forecast — then moves money only when a safe margin exists after accounting for known upcoming obligations.
That distinction matters. The system doesn’t look at today’s balance and guess whether it seems high enough. It looks at today’s balance minus known upcoming obligations and checks whether a safe margin still exists.
The forecasting logic breaks down into five steps:
- Income timing gets learned from historical deposits — weekly, biweekly, or irregular.
- Recurring bills get mapped to the calendar — rent on the 1st, insurance on the 14th, subscriptions scattered throughout the month.
- The engine projects a balance trajectory for the next 7 to 30 days.
- A safe transfer window gets flagged when the projected margin clears a defined buffer threshold.
- A micro-transfer moves to savings automatically during that window.
This is cash flow forecasting personal finance in practice — the same logic businesses use to manage runway, applied to an individual checking account.
How Does Cash Flow Forecasting Identify Safe Savings Windows?
A safe savings window is identified when your projected balance — after every known upcoming bill — still exceeds a defined minimum buffer. That’s the only moment predictive AI initiates a transfer.
It isn’t a fixed date on the calendar. It’s a dynamic signal based on what the forecast knows is coming.
Consider a gig worker paid on Tuesdays and Fridays, with rent clearing on the 1st. The forecasting engine learns that the window right after a Friday payout — before Monday’s subscriptions clear — is consistently safe. It never schedules a transfer the day before rent, because it already knows rent is coming.
The transfer amount varies with the margin available. In a tight week, it might move $8. In a stronger week, $45. No one decides either number manually — the forecast does.
Why Do Fixed Auto-Transfers Fail With Variable Income?
Fixed auto-transfers fail with variable income because they execute on a set schedule with no visibility into account trajectory, upcoming bills, or gaps between paychecks.
A $75 transfer scheduled for the 15th has no way of knowing a client payment expected on the 12th actually arrived on the 17th. It executes regardless. The overdraft follows. That’s the same failure loop as manual saving — just automated.
For anyone with irregular income, a fixed transfer carries the same overdraft risk as a manual one, minus the ability to pause it during a tight week.
Round-Up Savings vs. Predictive AI — When Does Each Method Work Best?
Round-up savings work best for steady income earners; predictive AI saving works best for irregular or gig income. The two methods solve different problems.
Round-up savings rounds every debit purchase to the nearest dollar and deposits the difference. It’s passive, low-risk, and generates slow accumulation — a useful supplementary layer, but not an emergency fund engine.
Predictive AI saving handles something different: larger, intentional transfers timed to your actual cash flow, sized to build a real three-to-six-month emergency fund without triggering overdrafts.
Round-Up Savings vs. Predictive AI — When Does Each Method Work Best?
Pick a view below to see how each method handles your income, risk, and saving goals.
Income Type
Best for steady, predictable paychecks where your balance rarely dips to zero.
Overdraft Risk
Low per transfer, since each round-up is tiny. But many small pulls can still add up on a thin balance.
Best Use Case
Passive, low-stakes saving that grows quietly in the background without you thinking about it.
Saving Precision
Low. It saves spare change on every purchase, not an amount tuned to your real cash flow.
Income Type
Built for irregular income — gig workers, freelancers, and anyone whose paydays shift around.
Overdraft Risk
Lowest. It forecasts upcoming bills and only moves money during a safe window your balance can handle.
Best Use Case
Building an emergency fund on variable income without triggering a single overdraft.
Saving Precision
High. Transfer size and timing adapt to your real cash flow, not a fixed date or spare change.
If your goal is a real emergency fund rather than spare change, forecasting-based automation is the approach built for it.
Who Benefits Most From Predictive Saving?
Predictive AI saving is built for people whose income timing is unpredictable — gig workers, freelancers, rideshare drivers, and hourly shift workers are the clearest beneficiaries.
Low-income earners and anyone building their first emergency fund on tight monthly cash flow are a close second. They’re the ones who can least afford a $35 overdraft fee erasing a week of progress.
If you manage income and expenses across separate accounts, it’s also worth reviewing the best digital banking apps for freelancers to ensure your primary checking account feeds a forecasting tool accurate data.
How Do You Set Up AI Saving for an Emergency Fund?
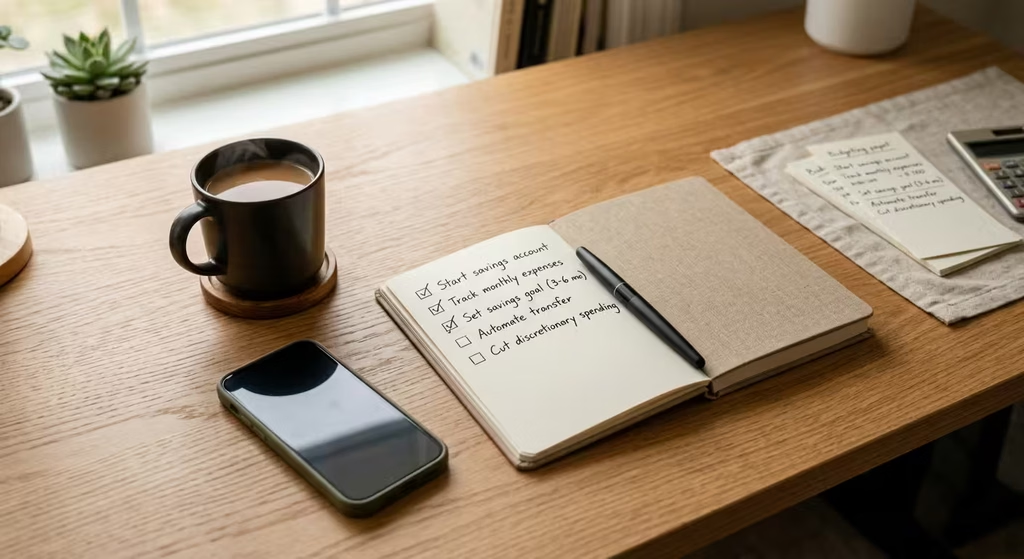
Setting up predictive AI for emergency fund saving takes six steps — and the most important one is giving the model enough time to learn your real income pattern before the first transfer runs.
- Link your income and primary spending accounts. The AI needs visibility into where money arrives and where recurring bills leave.
- Set a specific emergency fund target. Three to six months of essential expenses is the standard benchmark.
- Allow one to two pay cycles for pattern learning before transfers begin — skipping this calibration window reduces forecasting accuracy.
- Review and adjust your safe buffer setting. This is the floor the AI won’t transfer below. Set it higher if your bills cluster at the start of the month.
- Monitor the first few automated transfers and tweak the buffer if a transfer timing feels off relative to a known bill.
- Set monthly check-ins, not daily ones. Frequent manual overrides undermine the forecasting model’s ability to learn your real pattern.
Is AI-Based Saving Risk-Free? What Are the Limits?
No — predictive accuracy depends on data history, and sudden changes to your income or expenses can still cause miscalculations.
A few specific limits worth knowing before you connect an account:
- Forecasting needs calibration time. A new account with two weeks of history can’t build an accurate model yet.
- Sudden income gaps still catch the model off guard. A late-paying client or a lost shift can create a shortfall the AI didn’t anticipate.
- Data sync delays happen. If your bank connection lags by 24–48 hours, the AI may act on a stale balance.
- Human oversight still matters. Automated saving reduces bad timing — it doesn’t eliminate the need to occasionally check your accounts.
- Connecting a bank account means sharing transaction-level data. Favor platforms using read-only API access rather than your full login credentials. The NIST AI Risk Management Framework is a useful benchmark for how seriously a provider approaches AI safety. For a deeper look at what to check before linking accounts, Is Your Bank Data Safe With AI Apps? covers the specifics.
Fixed Transfer vs. Predictive Transfer: A Side-by-Side Scenario
In variable-income scenarios, predictive AI saving outperforms fixed auto-transfers primarily by eliminating overdraft losses — not by saving faster in ideal conditions.
Same person, same three-month goal, two approaches:
Fixed $75 transfer on the 15th: Two overdrafts occur when client payments arrive late in months one and three. Net savings after fees: roughly $125.
Predictive AI transfer: Amounts vary — $12 one week, $55 the next, $0 in a tight stretch. No overdrafts. Net savings after three months: roughly $310.
The difference isn’t speed. It’s that the predictive approach never gives back progress to a bank fee.
Which Tools Use This Mechanism?
A few platforms illustrate how cash-flow-based saving works in practice — these are examples of the mechanism, not a ranked list:
- Tilt times micro-transfers around upcoming bill windows, built specifically for variable-income users.
- Oportun applies predictive savings logic for low-income and thin-file users through small, frequent transfers.
- Acorns uses round-up logic rather than forecasting — a supplementary layer, not an emergency fund engine.
- Cleo adds a conversational pre-spend pause before discretionary purchases rather than cash-flow-based transfers.
For a fuller comparison of AI-powered budgeting and saving apps, 10 AI Budgeting Apps That Actually Save You Money covers the broader app landscape — this piece stays focused on the forecasting mechanism itself.
Start Saving on Your Terms
Emergency fund automation works when it’s built on cash flow forecasting — a system that times transfers around your real income and bill patterns, not a calendar date. For irregular-income earners, a fixed auto-transfer carries the same overdraft risk as manual saving. Predictive AI closes that gap by adapting to your actual cash flow instead of assuming a stable one.
Your next step doesn’t require signing up for anything yet. Pull up the last two months of your account history. When did income arrive? When did major bills clear? That pattern is exactly what a predictive AI system would learn. If the gaps are tight or unpredictable, forecasting-based automation is likely the better fit over a fixed schedule.
For a broader view of how AI is reshaping personal finance — investing, tax planning, and wealth automation beyond saving — The AI Wealth Revolution is the place to go next.
People Also Ask
How does predictive AI decide when to save money?
It builds a short-term cash flow forecast from your income history, bill schedule, and spending patterns. A transfer only happens when your projected balance — after all known upcoming obligations — clears a set minimum buffer.
Is AI savings automation safe for people with low income?
It can be — especially on platforms like Oportun built around lower and variable cash flows. Look for a configurable minimum buffer, small transfer amounts, and read-only API access. No system eliminates risk entirely, but overdraft-aware forecasting reduces it meaningfully compared to fixed transfers.
What is the difference between predictive saving and round-up saving?
Round-up saving passively saves the spare change from purchases — low risk, slow accumulation, best for steady income. Predictive saving times variable transfers around your real cash flow, making it better suited for building an emergency fund on irregular income.
Can I build an emergency fund with irregular income using AI?
Yes — irregular income is the specific use case predictive AI saving is designed for. It adjusts transfer amounts and timing to match your actual income pattern instead of assuming a fixed paycheck schedule.
How long does predictive AI take to learn my spending patterns?
Most platforms need one to two full pay cycles — roughly two to four weeks — before transfers reflect an accurate model. Transfers initiated before that calibration window tend to be less reliable.
AI Financial Operations · Editorial Integrity
Sources & Citations
Public reporting, platform information, and current market context behind this guide to predictive AI for savings — including automated savings tools, cash flow forecasting, round-up savings, behavioral finance AI, and personal finance automation.
Every major claim in this guide is grounded in public-facing platform materials, current reporting on AI-powered personal finance tools, and general market context around automated saving behavior. Product examples such as Tilt, Oportun, Acorns, Chime, Cleo, PocketGuard, and Whistl are included to illustrate how round-ups, cash flow forecasting, savings automation, and pre-spend interventions work in practice. Features, availability, security approaches, and performance claims can change, so readers should verify details directly with each provider before linking financial accounts or acting on a recommendation.
View full sources, methodology, and editorial notes
This article was written using a mix of direct article analysis, public-facing app and platform descriptions, general reporting on AI in consumer finance, and broad market context referenced in the piece itself. Preference is given to official company materials and clearly identified product positioning when explaining how automated saving tools work, what round-up savings does, how cash flow forecasting is described, and how behavioral prompts influence user action. Because app features, pricing, integrations, and security language can change quickly, this guide should be treated as educational information rather than financial, legal, or investment advice.
- Primary article context: Tech Capital Hub — Set It and Forget It: The Secret to Using Predictive AI for Hands-Off Saving — cited as the primary reference for the themes, examples, positioning, and platform comparisons used in this editorial sources block.
- Automated saving and cash flow-based transfers: Oportun — referenced for public-facing information on automated saving workflows designed around account activity, cash flow timing, and variable-income use cases.
- Round-up savings model: Acorns — referenced for the consumer round-up savings and investing model described in the article as a low-friction entry point for first-time savers.
- Banking-linked automatic saving features: Chime — referenced as an example of automated savings and round-up-style features integrated into a consumer finance app.
- Behavioral finance and conversational money guidance: Cleo — referenced as a consumer example of conversational personal finance interfaces and app-driven financial prompts.
- Budgeting and account monitoring context: PocketGuard — referenced for its public positioning around spending visibility, budgeting context, and account-aware money management tools.
- General market and industry context: Tech Capital Hub — AIFinOps Category — referenced for adjacent editorial coverage on AI in personal finance, fraud detection, financial data privacy, and automation themes connected to this article.
- Security and account-linking considerations: Plaid — referenced for general context around account connectivity infrastructure commonly used by fintech apps when users link financial accounts.
Predictive AI for Savings · Editorial Standards
Our Editorial Standards
Tech Capital Hub applies Google’s E-E-A-T framework to consumer fintech and AI coverage by favoring plain-English explanations, transparent sourcing, realistic examples, and clear disclaimers over hype. In this guide, we explain predictive AI for savings through practical use cases such as automated transfers, round-up savings, cash flow forecasting, and behavioral prompts. Where the article references app examples, market growth, security practices, or platform features, readers should verify the latest details directly with providers because product capabilities, pricing, integrations, and compliance language can change quickly.
View how our editorial standards apply to this article
Written for Everyday Savers, Not Finance Insiders
This guide is structured for readers who want to save more consistently but do not want a technical banking lecture. It starts with a relatable real-world scenario, then explains how predictive AI can move money automatically, identify safer transfer windows, and reduce reliance on willpower. The framing stays practical so readers can understand how these tools may fit real financial habits instead of an idealized budget.
Complex Fintech Concepts Explained in Plain English
Coverage breaks down key concepts such as cash flow forecasting, round-up savings, emergency fund automation, behavioral finance AI, and conversational app prompts without assuming prior expertise. Rather than overload the reader with technical jargon, the article explains what the systems do, why timing matters, and how automated saving behavior differs from traditional budgeting tools.
Grounded in Named Platforms and Public Context
The article uses named consumer finance platforms and publicly understandable product categories to anchor its claims. Examples such as Acorns, Chime, Oportun, Cleo, and PocketGuard help illustrate how round-ups, app-based savings automation, and account-aware financial prompts work in practice. Where market size, adoption, security, or feature claims are discussed, we present them as time-sensitive and avoid overstating permanence or certainty.
Clear About Limits, Risks, and Verification
We do not present savings apps as guaranteed outcomes or universal solutions. Automated tools may help some users save more consistently, but they still depend on income patterns, spending behavior, fees, account connectivity, and product design. This article is educational information only and not financial advice. Readers should review current terms, security practices, and provider disclosures before connecting accounts or acting on any platform recommendation.
AI Financial Operations · About the Author
Marcus Delray
Fintech Analyst · Founder of Tech Capital Hub
Marcus Delray is a fintech analyst and the founder of Tech Capital Hub. In this guide, he explains how predictive AI for savings works in practical terms — from cash flow forecasting and automated transfers to round-up savings and behavioral prompts — so readers can understand how modern saving tools help reduce friction and build consistency over time.
View full author bio, credentials, and links
Marcus Delray has spent over a decade researching financial technology. He built Tech Capital Hub to make that research useful for everyday readers — from complete beginners to business owners, operators, and finance-conscious consumers trying to make better decisions with modern tools. His coverage focuses on AI in finance, consumer fintech, business accounting software, blockchain, and automation.
For this guide, Marcus looks at a question that matters to everyday savers: how can AI help people save money without relying on willpower alone? He breaks down how predictive systems analyze income timing, recurring bills, and spending patterns to identify safer transfer windows, how round-up saving creates low-friction momentum, and how behavioral prompts can interrupt spending before it happens. Rather than present automation as magic, he explains the trade-offs clearly — including variable results, provider differences, account-linking considerations, and the need to verify current app features before acting. All content is educational information and not financial advice.
- Explains predictive AI for savings in plain language, including cash flow forecasting, automated transfers, and round-up saving models
- Breaks down how behavioral finance tools use timing, prompts, and reduced friction to help people save more consistently
- Covers consumer fintech platforms, AI-powered money tools, and practical personal finance workflows for non-experts
- Focuses on realistic trade-offs, including changing app features, provider differences, and account security considerations
- Grounds coverage in named platforms, public-facing product information, and clear educational framing rather than hype or financial advice
Enjoying our content?
Click below to add us as a preferred source. Google will prioritize our latest articles in your Top Stories, AI Mode, and AI Overviews.
Preferred Source on Google
2 thoughts on “How Predictive AI Builds Your Emergency Fund Without Over drafting — Even on Irregular Income”