Marcus has spent more than a decade researching financial technology and digital wealth systems. In this guide, he explains how AI wealth automation works across contributions, portfolio management, tax optimization, and goal tracking — and where human judgment still matters as portfolio complexity grows.
AI Wealth AutomationTax-Loss HarvestingPortfolio RebalancingDigital Wealth ManagementGoal-Based Investing
🔎
Independently researched using primary guidance and current framework references cited in the article, including IRS tax materials, NIST AI risk guidance, SEC/Investor.gov planning resources, CISA security recommendations, and FINRA investor alerts. This article is for general educational purposes only and does not constitute financial, investment, legal, or tax advice.
Daniel is a 38-year-old civil engineer in Denver. He earns a good salary and saves consistently. His money, however, was scattered.
He had a 401(k) at his current job and an old Roth IRA from his last one. He had a taxable brokerage account with a few ETFs and a block of company stock. About $40,000 sat in a high-yield savings account because he never decided where it should go. He had not rebalanced anything in three years.
Daniel was not careless. He just had no system.
Quick Answer: What Is AI Wealth Automation?
AI wealth automation is a connected system that uses artificial intelligence to automate investing, portfolio rebalancing, tax optimization, and goal tracking across your accounts — so your wealth grows steadily with less manual effort.
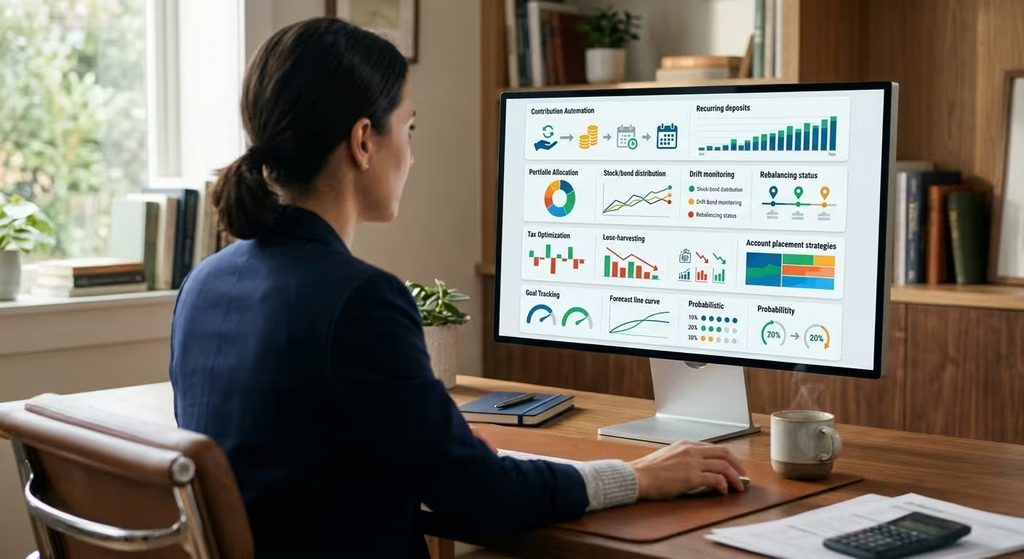
It is a category within digital wealth management. It is not a single app. It works across four layers: contributions, portfolio management, tax automation, and goal tracking. Each layer depends on the one before it.
This guide explains how to build that system: which layers matter, how tax automation works, which setup fits your portfolio size, and where a human should still be involved.
Key Takeaways
AI wealth automation has four layers: contributions, portfolio management, tax optimization, and goal tracking. Each layer depends on the one before it.
Your portfolio size should set your level of automation. Small portfolios need low costs and consistent habits. Larger taxable portfolios gain the most from tax automation.
Use one hub platform, not five. Stacking apps recreates the fragmentation you were trying to fix.
Tax-loss harvesting usually defers taxes rather than erasing them. Its value depends on your tax bracket, holding period, and how long you stay invested.
Add a human checkpoint as complexity grows. Equity compensation, business income, and estate questions still need a person.
AI Wealth Automation at a Glance
Comparison Table
AI Wealth Automation at a Glance
Compare AI wealth automation, robo-advisors, and human advisors across fit, strengths, limitations, tax features, and involvement level.
Comparison Point
Coordinated systemAI Wealth Automation
Low-maintenanceRobo-Advisor
Advisor-ledHuman Advisor
Best for
Multi-account investors who want coordinated tax and portfolio automation
Beginners who want simple low-maintenance investing
Complex households needing judgment and planning depth
Main advantage
Tax and portfolio coordination across accounts
Low cost, simple setup
Personalized advice and behavioral coaching
Main limitation
Requires setup, oversight, and goal input
Less customization, limited tax optimization
Higher cost, typically less frequent monitoring
Tax-loss harvesting
Yes, often daily
Sometimes, basic
Sometimes, manually
Human involvement
Optional checkpoint
None
Full
Interactive premium comparison block with horizontal scroll for smaller screens.
AI wealth automation matters less for picking market winners than for removing friction, tax drag, and portfolio drift — year after year.
Pros and Cons of AI Wealth Automation
Pros
Rebalances automatically when your portfolio drifts
Harvests tax losses across positions on a daily basis, not once a year
Coordinates contributions, tax moves, and goal tracking as one system
Reduces emotional decision-making during market swings
Scales as your portfolio grows
Cons
Requires accurate, up-to-date goal and income inputs to work well
Tax automation loses value in retirement-only accounts or low tax brackets
Wash sale mistakes can occur when multiple accounts are not fully visible to the system
Does not replace human judgment for complex situations like equity compensation or estate planning
Ongoing review is still required — automation does not mean abandonment
Table of Contents
What Is AI Wealth Automation?
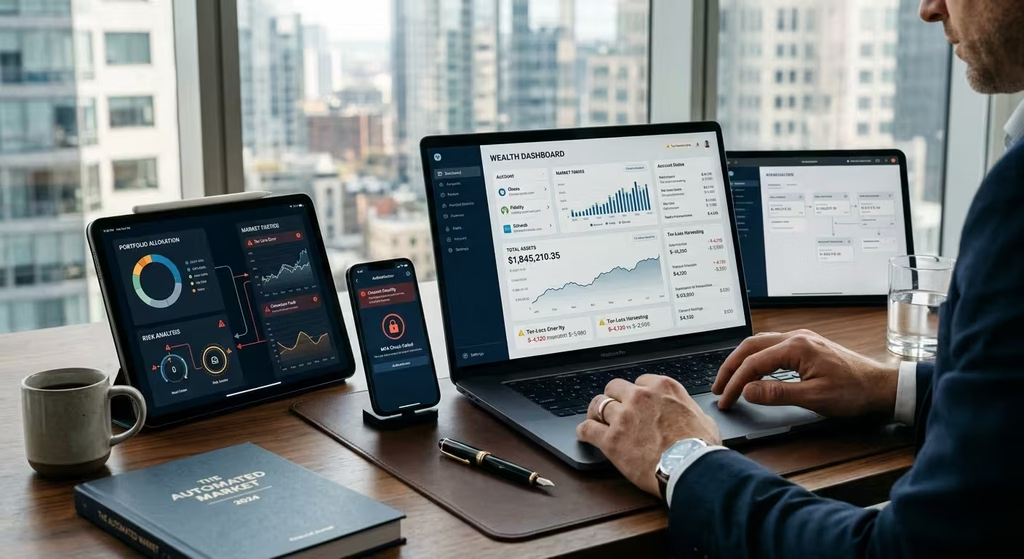
AI wealth automation is a set of connected tools that grow money you have already set aside. It is a digital wealth management approach that decides when to invest, keeps your asset allocation on target, captures tax savings, and tracks progress toward your goals.
It is not a single app. It is a system. The AI component comes from machine learning in finance and predictive financial modeling. These models watch your accounts continuously and act when conditions change — not on a fixed calendar.
AI Wealth Automation vs. Everyday Money Automation
These two ideas often get blurred, but they solve different problems.
Everyday money automation manages cash flow. It covers budgeting, spending analysis, bill timing, and overdraft alerts. If you want to understand that side, start with our guide on how AI is changing everyday personal finance.
AI wealth automation picks up where that leaves off. It works on money that is already invested or ready to be invested. The goal is long-term wealth accumulation, not monthly budget control.
Think of it this way. Cash flow tools keep money from leaking out. Wealth automation puts the money that stays to work.
Rules-Based Automation vs. AI-Driven Automation
Most people already use some automation. A recurring transfer on the 15th is automation. So is a fund that rebalances every quarter.
That is rules-based automation. It does the same thing on the same date, whatever the market is doing.
AI-driven automation is different. It decides when to act. It can rebalance only when a holding drifts too far from its target. It can harvest a loss on a volatile day. It can steer new deposits toward underweight assets instead of selling winners.
The difference is judgment within guardrails. You still set the rules. The system chooses the best moment to apply them.
Key Terms to Know
Key Terms to Know
Search the glossary to quickly find the definitions used throughout the article.
Term
What It Means
Direct indexing
Implementation method
An investment implementation method where you own the individual stocks inside an index instead of buying one fund that tracks it.
Tax-loss harvesting
Tax optimization
A tax optimization strategy used in taxable brokerage accounts: selling an investment at a loss to offset taxable gains, then buying a similar replacement to stay invested.
Rebalancing bands
Portfolio rule
Drift limits that trigger a rebalance — for example, act only if stocks move 5 percentage points away from target.
Asset location
Tax placement
Placing each investment in the account type where it is taxed most favorably.
Glide path
Planning concept
A planned shift toward a more conservative mix as your goal date approaches.
No matching terms found.
How AI Automates Wealth Building: The Four Layers
A working system stacks four layers. Skip one, and the others lose power. Here is how they fit together.
Layer 1: Contribution Automation
Everything starts with money moving into investment accounts. Without steady contributions, the other layers have little to work with.
Basic automation moves a fixed amount every payday. Smarter savings automation uses cash flow forecasting to time transfers around your bills. That way, an investment deposit never lands right before rent.
Get these right, and the rest of the system has fuel.
Layer 2: Portfolio Automation
This layer handles AI for portfolio management. It is a category within automated wealth management that builds a diversified portfolio based on your goals and risk tolerance — then keeps that portfolio on track.
Core tasks include:
Setting a target asset allocation, such as 80% stocks and 20% bonds
Monitoring drift as markets move
Rebalancing within bands, rather than on a fixed schedule
Directing new cash to underweight assets first, which reduces taxable selling
Robo-advisors are the most common way to run this layer. If you want to weigh providers, you can compare robo-advisor fees and features in our full breakdown. Some investors also hold digital assets. If that includes you, read our guide on automating a crypto allocation before mixing it into your core plan.
Layer 3: Tax Automation
This is where AI wealth automation earns much of its value. The system looks for tax-loss harvesting opportunities, manages direct indexing positions, and places assets in the right accounts.
Taxes are one of the few investing costs you can directly influence. Tax-aware investing will not make the market go up. It can, however, help you keep more of what the market gives you. The next major section covers this layer in full detail.
Layer 4: Goal Tracking and Course Correction
The final layer connects your money to your life. It answers one question: Am I on track?
Good platforms use predictive financial modeling to project outcomes. Many show a goal probability score — for example, “You have a 78% chance of reaching your retirement target.”
When something changes, the system suggests an adjustment. You might get a raise. You might push your target date back two years. You might decide you want a house sooner. The model then recalculates contributions, risk level, or timeline.
This turns retirement planning from a yearly worry into an ongoing, visible process.
How AI Automates Wealth Building: The Four Layers
Filter the table to focus on a specific layer or compare them all at once.
Layer
What It Automates
What You Still Decide
1. Contributions
Deposits into investment accounts
How much to save and which accounts get priority
2. Portfolio
Allocation, drift monitoring, rebalancing
Your risk tolerance and target mix
3. Tax
Loss harvesting, direct indexing, asset location
Which accounts the system can act on
4. Goals
Projections and course corrections
What you are saving for and by when
AI Tax Optimization: Where Wealth Automation Earns Its Keep
Tax efficiency is the clearest measurable advantage of an automated wealth system. Humans tend to harvest losses once a year, usually in December. Software can watch every position, every trading day.
Here is how it works and when it actually helps.
How Automated Tax-Loss Harvesting Works
Tax-loss harvesting is a tax optimization strategy used in taxable brokerage accounts. It follows a repeatable four-step cycle:
Detect. The system spots a position trading below your purchase price.
Sell. It sells that position to realize the loss.
Replace. It buys a similar, but not substantially identical, investment. Your market exposure stays roughly the same.
Record. The realized loss offsets capital gains. Unused losses can offset up to $3,000 of ordinary income per year, and the rest carries forward. The IRS rules on capital loss limits and carryovers explain exactly how this works.
The critical guardrail is the wash sale rule. If you buy a substantially identical security within 30 days before or after the sale, the loss is disallowed. According to IRS Publication 550 on wash sales, this applies even if your spouse buys the same security — or if you buy it inside your IRA or Roth IRA.
That last point is frequently missed. A loss disallowed because of an IRA purchase is not added to your basis in the new shares. It can be lost permanently. Your automation needs full visibility into every account you own, not just one.
Direct Indexing vs. ETF-Based Harvesting
Most robo-advisors harvest at the fund level. They swap one index ETF for a similar one when the whole fund drops.
Direct indexing is an investment implementation method that goes a level deeper. You own the individual stocks in the index. Even in a rising market, some stocks fall. Each falling stock is a separate harvesting opportunity.
In practice, direct indexing can create more tax-loss harvesting opportunities than ETF-level harvesting because individual stocks within an index decline at different times. How much more depends on market volatility, your contribution pace, and how long you have held the account. Be cautious with any provider claiming a fixed annual “tax alpha.” Real results vary widely.
Direct indexing has trade-offs:
Higher minimums. Many platforms require larger balances to access direct indexing.
More complexity. Hundreds of positions create more wash sale risk across accounts.
Tracking differences. Your returns can drift slightly from the index.
Diminishing returns. Early years often produce the most harvesting. As positions gain value over time, fewer losses appear.
For most investors, direct indexing becomes worth considering once taxable balances are large and they expect ongoing capital gains to offset.
Why Stable 2026 Tax Rules Help Automated Strategies
Tax optimization models work best when the underlying rules stay predictable. The One Big Beautiful Bill Act, signed July 4, 2025, made the individual income tax brackets from the 2017 tax law permanent. You can track updates on the IRS One Big Beautiful Bill resource page.
For automated systems, that stability matters. A model planning harvesting, gain realization, and Roth conversion decisions over decades is more reliable when brackets are not scheduled to expire. Long-range tax-smart investing becomes easier to model with confidence.
Some platforms also add deduction tracking. That is useful, but it is closer to tax preparation than wealth automation. Treat it as a bonus feature, not a core one.
When Tax Automation Is Not Worth It
Tax automation is powerful, but not universal. It adds little value in these cases:
Retirement accounts only. Gains and losses inside a 401(k) or IRA are not taxed year to year. There is nothing to harvest.
Low tax brackets. If your long-term gains already fall in the 0% capital gains bracket, harvesting losses offers little benefit.
Small taxable balances. Small losses produce small savings.
Very low turnover. If you rarely sell and have no other gains, harvested losses may sit unused for years.
One more honest point. Harvesting lowers your cost basis, so you may owe more tax later when you sell. In many cases, it defers tax rather than eliminating it. The real gains come from offsetting high-tax short-term gains, the $3,000 ordinary income offset, and long holding periods. Inherited assets generally receive a basis stepped up to fair market value at death, which can erase deferred gains entirely.
How to Build Your AI Wealth Automation Setup by Portfolio Size
There is no single best setup. Your investable assets shape which layers matter most. Use this framework as a starting point.
Under $100,000: Automate the Basics
At this stage, low costs and consistent habits beat advanced tax strategies.
Choose one low-cost platform that automates contributions and rebalancing. Robo-advisors with low or no advisory fees work well here. If you are starting from scratch, our guide to choosing a first robo-advisor walks you through the basics.
Focus on three things:
Capture your full employer match
Automate monthly contributions
Pick a diversified portfolio that matches your risk tolerance
Tax automation can wait. Wealth accumulation at this level comes mainly from saving rate and time in the market.
$100,000 to $500,000: Add Tax Automation
This is where tax-loss harvesting starts to pay off, especially in taxable accounts. Turn on automated harvesting if your platform offers it. Consider direct indexing if your taxable balance is substantial and you expect future capital gains.
$500,000 to $2 Million: Automated Core, Human Checkpoint
Let AI run daily management, rebalancing, and tax moves. Then add one annual review with a flat-fee planner.
That planner is not there to replace the system. They are a checkpoint. They catch what automation often misses:
Restricted stock units (RSUs) and stock option timing
Business or rental income
Concentrated company stock positions
Estate and beneficiary questions
A good planner also provides behavioral coaching. When markets fall sharply, a calm second opinion can prevent a costly panic decision. If you are weighing that trade-off, read when a human advisor still wins.
$2 Million and Above: Human-Led, AI-Supported
At this level, the plan often involves trusts, multi-generational goals, and complex capital allocation across several entities. A human advisor should lead. AI supports with daily monitoring, predictive modeling, and harvesting.
How to Build Your AI Wealth Automation Setup by Portfolio Size
Use the filters to isolate the portfolio tier most relevant to your readers.
Portfolio Size
Automation Level
Layers to Turn On
Human Role
Main Risk to Watch
Under $100K
AI only
Contributions, portfolio
None required
High fees eroding small balances
$100K–$500K
AI-primary
All four, plus harvesting
Optional
Wash sales across accounts
$500K–$2M
Hybrid
All four, plus direct indexing
Annual checkpoint
Equity compensation and concentration
$2M+
Human-led
All four, as support tools
Lead advisor
Estate and entity complexity
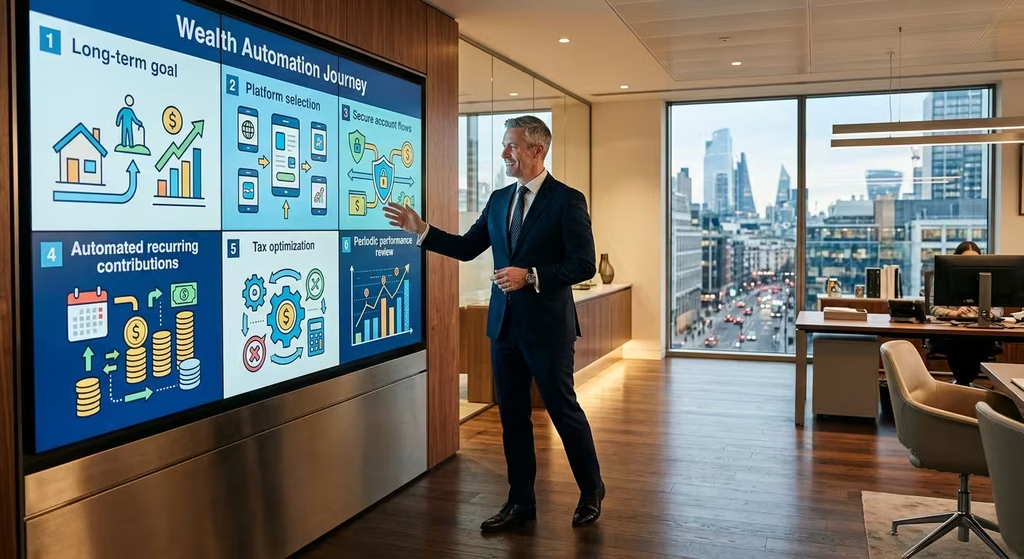
How to Automate Wealth Building With AI: A 6-Step Setup
Here is a practical path from scattered accounts to a working system.
Step 1: Define One Wealth Goal and Timeline
Start with a single, specific goal. “Retire at 60 with $2 million” works. “Save more” does not.
Your goal and timeline drive everything else. Goal-based investing lets the system assign the right risk level and glide path. If you need help sizing a realistic goal, the SEC’s free financial planning tools on Investor.gov include retirement and savings calculators.
Step 2: Choose One Hub Platform
Pick one primary platform to run your wealth system. Resist the urge to stack several.
Judge platforms on function, not design:
Tax features. Does it offer harvesting or direct indexing at your balance level?
Account types. Can it hold your taxable, IRA, and Roth accounts together?
Explainability. Does it tell you why it made each trade?
Cost. Do fees make sense for the features you will actually use?
Link every investment account, even ones the platform will not actively manage. Full visibility prevents wash sale mistakes and gives your projections an accurate picture.
Then set guardrails. Decide what the system can do automatically and what requires your approval. A practical split:
Automatic: rebalancing within bands, harvesting in taxable accounts, investing new deposits
Requires approval: selling concentrated positions, large withdrawals, changing your risk level
Turn on multi-factor authentication for every connected account. The U.S. Cybersecurity and Infrastructure Security Agency explains why in its guide to multifactor authentication.
Step 4: Automate Contributions
Set recurring deposits into each account. For most investors, prioritize in this order:
Employer match in your 401(k)
Roth or traditional IRA, depending on your tax situation
Additional 401(k) contributions up to the annual limit
Taxable brokerage account
Coordinate your employer plan with your hub platform. Your 401(k) holdings count toward your overall asset allocation, even if a separate provider manages them.
Step 5: Turn On Tax Automation
Enable harvesting in taxable accounts. Then verify three settings:
Cross-account wash sale protection. The platform must know about your IRAs and any spouse accounts.
Asset location. Hold tax-inefficient assets — such as taxable bonds — in tax-advantaged accounts where possible.
Replacement securities. Confirm the platform swaps into investments that are similar but not substantially identical under IRS rules.
Step 6: Review Quarterly, Rebuild Annually
Automation does not mean abandonment. Block one hour each quarter to check:
Allocation drift
Losses harvested year to date
Goal probability score
Any unexpected trades
Once a year, rebuild from the top. Revisit your goal, timeline, income, and risk tolerance. Also rebuild after any major life event — marriage, a new child, a job change, or an inheritance.
Agentic AI and the Next Stage of Wealth Automation
Early automation followed single rules. Agentic AI — a more advanced category of AI systems — handles multi-step tasks from one plain-language instruction.
From “Set It and Forget It” to “Tell It What You Want”
Imagine typing, “Optimize my portfolio for tax efficiency this year.” An agentic system can:
Review every position across your accounts
Identify losses worth harvesting
Check for wash sale conflicts
Model how the trades affect your tax bracket
Update your retirement projection
Request your approval before acting, if your guardrails require it
You state the outcome. The system plans the steps. This is the direction consumer wealth platforms are moving.
What Agentic Automation Still Cannot Do
Agentic systems are strong at calculation and coordination. They struggle with judgment calls.
They cannot know how you will feel watching your account drop 25%. They cannot weigh your values against your returns without clear input from you. They cannot fully account for the emotional complexity of a divorce, an inheritance, or caring for an aging parent.
More autonomy also requires stronger oversight. The NIST AI Risk Management Framework stresses human oversight, transparency, and ongoing monitoring of AI systems. Those principles apply directly when software has authority to move your money.
Risks and Limits of AI Wealth Automation
Every system has failure points. These are the risks specific to automated wealth building.
Over-Automation and Disengagement
The biggest risk is not a bad algorithm. It is an owner who stops paying attention.
When no one reviews the system, small errors compound quietly. A wrong goal setting or outdated income figure can run unchecked for years. Your quarterly review is the essential safeguard.
Tax Automation Errors
Tax automation can backfire when it lacks full information. Common problems include:
Wash sales across platforms. One app harvests a loss while another buys the same fund inside your IRA.
Harvesting in the wrong account. Selling inside a retirement account produces no tax benefit.
Cost-basis gaps. Transferred accounts sometimes arrive with missing or incorrect basis data.
Review your year-end tax forms carefully. If something looks off, contact the platform before filing.
Model Drift and Bad Inputs
AI is only as good as its inputs. If your income doubled but your profile still shows the old number, the system plans for the wrong life. The same problem applies to outdated goals, timelines, or risk tolerance answers.
Generative AI tools add a separate risk: confident but incorrect answers. NIST’s Generative AI Risk Management Profile flags this issue directly. Use purpose-built financial platforms for real decisions — not general-purpose chatbots.
Security Basics Before You Connect
Before linking any account, confirm three things:
Read-only access where possible, with clear limits on what the platform can move
Multi-factor authentication on every connected account
A clear privacy policy that explains how your data is stored and shared
Stacking several apps. You recreate the same fragmentation you started with, plus added wash sale risk.
Enabling harvesting without checking all your accounts. Your IRA, Roth IRA, and your spouse’s accounts all count.
Skipping the human checkpoint once your portfolio exceeds $500,000. Equity compensation and estate planning are easy for software to mishandle.
Choosing a platform based on its interface. Tax features and explainability matter far more than design.
Not updating your goals after major life changes. Old inputs lead to wrong decisions.
People Also Ask
What is AI wealth automation?
AI wealth automation is a digital wealth management approach that uses artificial intelligence to automate investing, portfolio rebalancing, tax optimization, and goal tracking across multiple accounts — with less manual effort. It operates across four layers: contributions, portfolio management, tax automation, and course correction. The goal is steady, long-term wealth accumulation without constant hands-on management.
Is AI wealth automation worth it?
For most investors with taxable accounts, yes — especially for portfolio rebalancing and tax-loss harvesting. Basic contribution and rebalancing automation helps nearly everyone. Tax automation becomes significantly more valuable once taxable balances grow, generally beyond $100,000. If all your money sits inside retirement accounts, automated tax-loss harvesting adds little measurable benefit.
How does AI automate tax-loss harvesting?
The system monitors positions daily, sells those trading below their purchase price, and immediately buys similar — but not substantially identical — replacements to maintain market exposure. Realized losses offset capital gains and up to $3,000 of ordinary income per year. Good platforms also enforce wash sale rules across all connected accounts, including IRAs and spouse accounts.
How much money do I need to start?
You can start with very little. Many robo-advisors have low or no minimums for contribution and rebalancing automation. Direct indexing and advanced tax features typically require larger taxable balances. Start with the basics now and add tax automation layers as your taxable portfolio grows.
When should I add a human advisor to my automated setup?
Consider adding a human checkpoint once your portfolio passes approximately $500,000, or sooner if your situation becomes complex. Equity compensation, business income, inheritances, trust planning, and estate questions all benefit from human judgment that AI systems are not well positioned to provide. A flat-fee annual review often gives the right balance of cost and oversight.
How often should I review an automated wealth system?
Review it quarterly and rebuild it annually. Each quarter, check allocation drift, year-to-date harvested losses, goal probability score, and any unexpected trades. Each year, revisit your goal, income, timeline, and risk tolerance. Also review after any major life event: marriage, a new child, a job change, or an inheritance.
Can I automate wealth building across multiple accounts?
Yes, but coordination across all accounts is essential. Link every investment account — including ones the platform will not actively manage — so it can prevent wash sales and optimize asset location. Your 401(k), IRAs, taxable accounts, and your spouse’s accounts all affect your tax outcomes and overall asset allocation.
Conclusion: What an Automated Wealth System Looks Like Six Months In
Daniel did not overhaul everything in a weekend. He followed the steps.
He set one goal: financial independence by 58. He chose one hub platform and linked all four accounts. He moved most of the idle $40,000 into his taxable account in planned stages. He turned on harvesting and set guardrails around his company stock.
Six months later, his contributions ran on their own. His allocation sat back on target. A few harvested losses helped offset the gains from trimming his concentrated company stock. His goal probability score had climbed.
He spends about one hour each quarter reviewing the system. That is it.
That is the real promise of AI wealth automation. Not overnight riches. Just the quiet removal of friction, delay, and avoidable tax drag — year after year.
Key points to carry forward:
Build all four layers, in order
Match your automation level to your portfolio size
Use one hub platform with full account visibility
Keep a human checkpoint as complexity grows
Your next step: Find your portfolio tier in the table above and complete Step 1 this week. Write down one specific goal and one target date. The system can build from there.
Personal Finance · Editorial Integrity
🛡️
Sources & Citations
Primary guidance and current public references behind this guide to AI wealth automation, including tax-loss harvesting rules, AI risk oversight, investor planning tools, account security, and investor protection.
AI Wealth AutomationTax-Loss HarvestingRetirement PlanningSecurity & PrivacyInvestor ProtectionReviewed 2026
This guide is based on primary public references and named institutional guidance wherever possible. Tax mechanics are grounded in IRS rules, oversight and governance references come from NIST, planning tools come from Investor.gov, and account security guidance comes from CISA and FINRA. Because tax guidance, provider features, and platform practices can change, readers should always verify current details before making financial, tax, or investment decisions.
View full sources, methodology, and editorial notes⌄
This article was written using a mix of primary regulatory and institutional sources, investor education materials, and current public guidance relevant to automated wealth systems. Preference was given to primary documentation where it directly supports a claim about tax-loss harvesting, wash sale rules, capital loss carryovers, AI oversight, planning tools, authentication, privacy or investor fraud prevention. Platform examples in the article are descriptive, not endorsements. This article is educational information and not financial, tax, investment, or legal advice.
Wash sale rules:IRS Publication 550 — Wash Sales
— cited for the 30-day wash sale rule and the importance of avoiding substantially identical purchases across accounts.
Current IRS tax law update page:IRS — One Big Beautiful Bill Resource Page
— cited for the article’s reference to stable long-range tax planning assumptions after the 2025 law change.
Multifactor authentication guidance:CISA — Multifactor Authentication
— cited for account security best practices when linking financial accounts to digital wealth platforms.
AI oversight and governance framework:NIST AI Risk Management Framework
— cited for oversight, transparency, and human-governance principles relevant to automated financial systems.
Generative AI reliability and risk:NIST Generative AI Risk Management Profile
— cited for the risk of confident but incorrect AI-generated outputs in financial decision contexts.
Tech Capital Hub applies Google’s E-E-A-T framework to every personal finance guide by prioritizing plain-English explanations, primary public guidance, and transparent limitations over hype or vague financial promises. In this article, we explain AI wealth automation as a system — not a shortcut — and anchor key claims to authoritative references where they matter most: IRS materials for tax-loss harvesting and wash sale rules, NIST guidance for AI oversight, Investor.gov for planning tools, and CISA and FINRA resources for security and investor protection. Where outcomes depend on changing tax rules, provider features, or individual circumstances, we say so clearly instead of overstating certainty.
View how our editorial standards apply to this article⌄
💬
Experience
Built Around Real Investor Decisions
This guide is written for readers trying to turn scattered accounts into a functioning wealth system. Instead of treating automation as abstract fintech jargon, it follows the practical decisions investors actually face: where contributions should go, when tax automation matters, how portfolio size changes the right setup, and when a human checkpoint becomes necessary.
🧠
Expertise
Complex Concepts Explained in Plain English
The article breaks down tax-loss harvesting, direct indexing, rebalancing bands, asset location, and predictive goal tracking without assuming prior knowledge. Technical concepts are translated into practical use cases, so readers can understand not just what a platform does, but why that function matters and where its limits begin.
📚
Authoritativeness
Primary Sources Where Claims Need Proof
Specific factual claims are grounded in primary or institutional references. IRS Publication 550 supports the explanation of capital loss offsets and wash sales, NIST materials support the discussion of AI risk oversight, Investor.gov supports planning and goal-setting references, and CISA and FINRA provide the article’s security and fraud-prevention context.
🛡️
Trustworthiness
Clear About Limits, Trade-Offs, and Risk
We state plainly that automation is not the same as judgment. The guide is explicit about where tax automation adds little value, where wash sale mistakes can happen, why general-purpose AI tools can be unreliable for financial decisions, and why higher-net-worth households still need human oversight. Nothing here is presented as personal financial, tax, investment, or legal advice.
Personal Finance · About the Author
Marcus Delray
Fintech Analyst · Founder of Tech Capital Hub
Personal FinanceDigital Wealth ManagementAI in FinanceTax Optimization
Marcus Delray is a fintech analyst and the founder of Tech Capital Hub. In this guide, he explains how AI wealth automation works across contributions, portfolio management, tax optimization, and goal tracking — and where human judgment still matters as financial complexity grows. His focus is on practical systems, plain-English explanations, and realistic trade-offs rather than hype.
View full author bio, credentials, and links⌄
Marcus Delray has spent over a decade researching financial technology. He built Tech Capital Hub to turn complex money topics into clear, practical guidance for everyday readers — especially where digital systems, automation, and real financial decisions overlap.
For this guide, Marcus breaks AI wealth automation into the parts that matter most in real life: where contributions go first, how automated portfolio management works, when tax-loss harvesting adds real value, how direct indexing changes the equation, and why goal tracking matters more than product marketing. He also explains where automation can fail — including wash sale mistakes, poor inputs, over-automation, and security gaps — and why larger portfolios often need a human checkpoint. The goal is not to sell readers on software, but to help them understand what a functioning automated wealth system actually looks like in practice.
Explains AI wealth automation in plain language across contributions, portfolio management, tax optimization, and goal tracking
Breaks down tax-loss harvesting, wash sales, direct indexing, and rebalancing without relying on vague fintech jargon
Connects platform features to real investor decisions, including portfolio size, taxable account value, and human oversight needs
Grounds coverage in public guidance and institutional references where factual claims need support
Frames all content as educational information rather than financial, tax, investment, or legal advice
Marcus Delray is a fintech analyst and founder of Tech Capital Hub, where he covers AI in finance, blockchain technology, DeFi, and business accounting tools. With over a decade of experience researching financial technology, he writes to make complex fintech topics
actionable for investors, entrepreneurs, and finance professionals.All content is independently researched. Affiliate disclosures apply where relevant. Nothing on this site constitutes financial advice.