Freelancer Bank Account vs Personal Account: Which Should You Use?
Senior Fintech Editor & Analyst · Tech Capital Hub
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering digital banking, payments, and compliance for freelancers and small businesses. In this guide, he explains when freelancers can use a personal checking account, when a business account makes more sense, and how account structure affects taxes, bookkeeping, legal separation, and future financing.
Quick Answer: Can Freelancers Use a Personal Bank Account?
Yes. Most sole proprietors can legally use a personal checking account for freelance income — no federal rule requires a separate one. But a dedicated business account is usually the better long-term choice because it makes taxes easier to document, bookkeeping cleaner, legal separation stronger for LLC owners, and loan applications more credible.
In short:
- Is it legal? Usually yes, for sole proprietors.
- Is it smart long-term? Usually not. Mixed accounts make your records harder to prove.
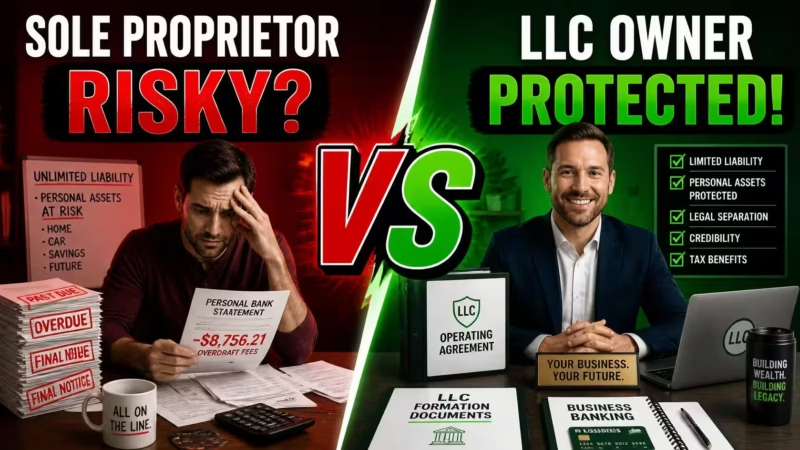
- Do LLC owners need one? A separate account is strongly recommended to protect your liability shield.
- What’s the best move? Open a business checking account for freelancers. Then route all freelance income and expenses through it.
When you’re ready to compare providers, start with our guide to the best digital banking apps for freelancers.
Why This Choice Matters More Than It Seems
Emily is a freelance copywriter who ran client payments and personal spending through one checking account for three years. Then the IRS sent a letter asking her to support the business expenses on her tax return.
The letter wasn’t an accusation. It was a request for proof.
Her accountant spent about 20 hours separating business transactions from personal ones. The bookkeeping cleanup cost $2,800 — far more than a dedicated business account would have cost over the same period.
The lesson is simple. Mixing accounts rarely breaks a rule. It raises the cost of proving your financial records are accurate.
In this guide, you’ll learn:
- Whether using a personal account for freelance work is legal
- How mixed accounts affect taxes, audits, and bookkeeping
- Why LLC owners face higher legal stakes
- How your account history shapes future financing
- How to switch to a business account step by step
Freelancer Bank Account vs Personal Account: Side-by-Side Comparison
Here’s how the two setups compare on the factors that matter most.
Freelancer Bank Account vs Personal Account
This side-by-side comparison shows where a personal checking account can work, where a business account gives you cleaner operations, and why separation becomes more important as freelance income grows.
Bottom line: A personal account can work for some new sole proprietors, but a business account usually becomes the cleaner, safer, and more scalable choice once freelance income is steady.
Cost is rarely a real barrier anymore. Many online business bank accounts now offer no-monthly-fee plans. Our roundup of the best free business bank accounts for freelancers lists the strongest zero-fee options.
Which Account Fits Your Situation?
The right setup depends on your structure, income, and plans. Find your situation below.
Which Account Fits Your Situation?
The best account setup depends on how often you freelance, whether you operate through an LLC, and how important clean records are for taxes, bookkeeping, and future financing.
Bottom line: A personal account may be workable at the very beginning, but once freelance income becomes regular, a business account usually gives you cleaner records, easier tax prep, and better long-term flexibility.
For most working freelancers, a self-employed bank account pays for itself in saved time alone.
Table of Contents
What Is Commingling, and Why Does It Cause Problems?
Definition: Commingling Funds
Commingling means running business and personal money through the same bank account. It makes it harder to show which transactions belong to your business.
What Commingling Looks Like Day to Day
- A client payment lands next to your grocery charges.
- Your design software renews beside a personal streaming plan.
- Your quarterly estimated taxes come from the same balance as your rent.
Most new freelancers commingle because a second account feels like extra work. It is a little extra work. But that small effort prevents much bigger costs later.
Is It Illegal to Use a Personal Account for Freelance Work?
In short: No. For most sole proprietors, it’s legal. The risks are practical, not criminal.
Can a Sole Proprietor Use a Personal Bank Account?
Yes. The IRS does not require sole proprietors to keep a separate business account. What the IRS does require is good records. According to its recordkeeping guidance for small businesses, you must keep records that support your income and deductions.
So a personal account is allowed. It just makes that recordkeeping harder.
Can Your Bank Restrict Business Use of a Personal Account?
Sometimes. Some banks limit commercial activity in their personal account terms. Heavy business use may trigger an account review or even closure.
Check your own account agreement. Look for language about “commercial use” or “business purposes.”
Does an LLC Need a Separate Bank Account?
No federal rule requires it. Even so, it’s strongly advised. Your LLC’s liability protection depends on keeping business and personal money apart. We cover this in detail in the LLC section below.
How Mixed Accounts Affect Your Taxes and Audit Readiness
In short: A separate account doesn’t change what you owe. It changes how easily you can prove your numbers are right.
Every Deduction Needs a Clear Business Purpose
Sole proprietors report business income and expenses on Schedule C (Form 1040). Single-member LLCs usually do too, unless they choose a different tax treatment.
Your business expense deductions must be ordinary and necessary business expenses. The IRS defines an ordinary expense as one that’s common in your field. A necessary expense is one that’s helpful and appropriate for your business. You can review the rules in the IRS guide to deducting business expenses.
Common freelancer deductions include:
- Software and subscriptions
- Computers and equipment
- Home office deductions, if you qualify under the IRS home office deduction rules
- Professional development and courses
None of these are automatic. Each one needs receipts and documentation. In a business-only account, the business purpose is clear by default. In a mixed account, someone has to rebuild it.
What a Separate Account Does (and Doesn’t) Do for Your Taxes
A business account won’t lower your self-employment tax. It won’t change your tax rate either. You can learn how self-employment tax works on the IRS site.
What it does change:
- Fewer missed deductions. Real expenses don’t get dropped because no one can label them.
- Fewer accidental overclaims. Personal charges don’t slip into your business totals.
- Lower prep fees. Your accountant spends less time sorting transactions.
Do You Still Owe Tax Without a 1099-NEC or 1099-K?
Yes. All freelance income is taxable, whether or not you get a form.
Reporting thresholds have recently changed. According to IRS guidance, the Form 1099-NEC threshold rose from $600 to $2,000 for payments made after 2025 under the One Big Beautiful Bill Act. The 1099-K threshold for payment apps and card processors returned to $20,000 and more than 200 transactions. These thresholds can and do change, so always verify the current rules directly on the IRS pages for Form 1099-NEC and Form 1099-K before filing.
Fewer forms do not mean less scrutiny. You still have to report every dollar. A business-only account gives you one clean source for your income total.
How a Business Account Helps During an IRS Audit
In short: A separate account won’t prevent an IRS audit. It makes responding faster, cheaper, and less stressful.
During an IRS examination, an examiner may ask for bank statements. They can compare your deposits with the income you reported. The IRS explains the process on its IRS audits page.
With a mixed account, you must explain every unclear deposit. Was it a client payment? A refund? A transfer from a friend? With a business account, your audit trail already tells the story.
Clean Records Support the QBI Deduction
According to the IRS, many self-employed individuals may qualify for the qualified business income deduction. The QBI deduction can allow eligible owners to deduct a portion of their qualified business income, though income limits, business type, and other factors affect eligibility. The One Big Beautiful Bill Act extended and made the deduction permanent, but the rules remain subject to IRS guidance.
The details depend on your income and type of work. Review the IRS overview of the qualified business income deduction or ask your tax pro.
Here’s the key point. The deduction is based on your net business income. Clean records make that number easier to support.
Plan for Quarterly Estimated Taxes
No employer withholds taxes for you. That’s why most freelancers pay quarterly estimated taxes.
A dedicated account makes this simple. Set aside a fixed share of every client payment. Then pay your estimates from that reserve. You can even automate quarterly freelance tax savings so the money moves on its own.
Key takeaway: A separate account won’t cut your tax bill by itself. It makes your deductions easier to document, cheaper to prepare, and easier to defend.
How Commingling Turns Bookkeeping Into Reconstruction
In short: Mixed accounts turn bookkeeping into detective work. A business account gives your software and accountant clean data from day one.
What Bookkeeping Cleanup Actually Involves
When accounts are mixed, your bookkeeper has to:
- Review every statement line by line
- Flag charges that might be business-related
- Request missing receipts from you
- Run reconciliation against your invoices
- Rebuild totals for each expense category
That work is billed by the hour. The more transactions you have, the higher the bill. All of it exists because of commingling.
A business account flips the default. Every transaction is presumed to be for business. The rare personal charge stands out and gets fixed fast.
Why Accounting Software Works Better With a Business Account
Tools like QuickBooks and Xero categorize transactions automatically. But they need clean input to give you clean output.
Feed them rent, groceries, and client payments together, and the software guesses. Then you check every guess by hand. Feed them business-only data, and categories become reliable. Your profit and loss statement (P&L) becomes accurate enough to trust.
If you already use these tools, see our list of banking apps that sync with QuickBooks and Xero.
Built-In Tools From Digital Business Banking Platforms
Many digital business banking platforms now include bookkeeping and tax tools:
- Found offers tax estimates and expense tracking built for Schedule C filers.
- Lili offers automatic tax savings buckets that fill as income arrives.
- Holdings offers AI-assisted categorization and real-time P&L reports.
Features and pricing change often. Always check each provider’s current terms. Some platforms also handle billing. Our guide to freelance banking apps with invoicing compares those options.
Key takeaway: Messy bookkeeping is usually an account structure problem, not an accounting problem. Fix the structure, and most of the mess disappears.
Why LLC Owners Face Higher Legal Stakes
In short: For LLC owners, a separate account helps protect the line between personal and business assets. Commingling can weaken that line if the business is ever sued.
What Is Piercing the Corporate Veil?
Piercing the corporate veil happens when a court holds an owner personally liable for business debts. Courts do this when the owner and the business didn’t truly operate as separate entities. Cornell Law School’s Legal Information Institute offers a plain-language overview.
Factors Courts Commonly Consider
Rules vary by state. Still, courts often look at whether the owner:
- Paid personal expenses from business funds
- Failed to keep separate financial records
- Never kept a dedicated business account
- Pulled money out in ways that hurt creditors
One stray charge rarely collapses the shield. But a pattern of commingling gives the other side strong evidence.
How a Separate Account Supports Personal Asset Protection
An LLC’s main benefit is limited liability. Your home, car, and savings are generally shielded from business debts and lawsuits. That shield depends on the LLC acting as its own entity.
A dedicated account is your clearest proof of that separation. Every business dollar stays in the business. Every personal dollar stays personal. When you pay yourself, you record it as an owner’s draw.
This matters even for a single-member LLC. The IRS often treats a single-member LLC as a “disregarded entity” for tax purposes. But state law still treats it as a separate legal entity. Your banking should reflect that.
What Sole Proprietors Should Know
Sole proprietors have no liability shield to lose. You and your business are legally the same person.
Clean records still help you. In a client dispute, a business statement that matches your invoices is strong evidence. And if you form an LLC later, your habits will already be in place.
Not sure which structure fits you? Compare sole proprietor vs LLC bank account requirements before you decide. The SBA’s guide to choosing a business structure is also a helpful starting point.
Key takeaway: For LLC owners, a separate account isn’t just tidy bookkeeping. It’s part of keeping the protection you formed the LLC to get.
How Your Account History Affects Loans and Financing
In short: Lenders judge your business by its cash flow. Mixed accounts make that cash flow hard to read. That can make you look riskier than you are.
What Lenders Review Before Approving Freelancers
When you apply for a business loan, lenders often ask for:
- Recent business bank statements
- A profit and loss statement
- Tax returns, including Schedule C for sole proprietors
- Sometimes a balance sheet
Many lenders run a cash-flow analysis to evaluate whether your business generates enough income to cover its obligations. They may also calculate your debt-service coverage ratio, or DSCR — a measure that compares your business cash flow against your total debt payments. A DSCR above 1.0 generally means your business earns more than it owes in payments, but lender minimums vary by institution, loan type, and risk assessment. Confirm current underwriting requirements directly with your lender or the SBA before applying.
If you’re exploring government-backed options, review the requirements for SBA 7(a) loans. SBA lending rules change over time, so confirm current guidance with the SBA or your lender.
Why Mixed Accounts Can Slow Down Approval
Picture an underwriter reading your statements. Client payments come in. Then money leaves for groceries, vacations, and rent. Is that a business expense? Is it profit taken out?
The underwriter can’t tell. Personal withdrawals can look like cash leaking from the business. That doesn’t guarantee a denial. But it often means more questions, more paperwork, and a slower review.
Building Business Credit History Starts Now
Lenders want a track record. You can’t create that history after the fact.
A clean business account builds the business credit history you’ll need later. It helps whether you want a business line of credit for slow months or invoice factoring and invoice financing to speed up cash from unpaid invoices.
Key takeaway: Treat clean account history as an asset. Every month you build it now makes future financing easier.
Do Freelancers Need a Separate Business Bank Account?
In short: LLC owners should treat it as essential. Sole proprietors don’t need one by law, but most benefit once income becomes steady.
If You Run an LLC
Open one. Your liability protection depends on separate finances. The SBA also recommends that new businesses open a business bank account for legal protection and simpler taxes.
If You’re a Sole Proprietor
It’s optional. But it’s time to switch when any of these apply:
- You claim several business expense deductions each year
- You work with an accountant or use accounting software
- You pay quarterly estimated taxes
- You may apply for financing in the next few years
- You plan to form an LLC
Most freelancers hit at least one of these once income becomes regular. That’s the point where a business account starts saving more than it costs.
Key takeaway: The real question isn’t whether you need a business account today. It’s whether you want clean records or a cleanup bill two years from now.
How to Switch From a Personal to a Business Bank Account
In short: Most freelancers can open an account and redirect income within a week. The work is simple and far cheaper than cleaning up mixed records later.
Step 1: Choose and Open the Account
You can choose a traditional bank or a neobank. Popular digital options include Mercury, Found, and Lili. Many let you apply fully online in under an hour, though verification may take a few days.
Some digital platforms partner with banks for deposit coverage. Before you deposit, check how protection works using the FDIC’s deposit insurance guide.
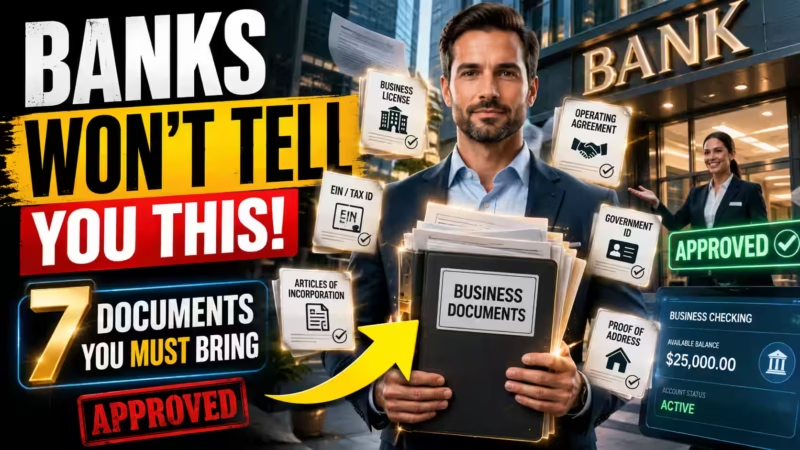
Requirements vary by provider and business type. You’ll typically need:
- A government-issued photo ID
- Your Social Security number or an Employer Identification Number (EIN)
- Your business name, or your own legal name as a sole proprietor
- Business formation documents if you run an LLC
You can apply for an EIN for free through the IRS EIN application page. For a full checklist, see the documents needed to open a business bank account.
Can I open a business bank account without an LLC? Yes. Sole proprietors can usually open one with an SSN or EIN. If you use a business name other than your own, you may need a DBA certificate.
Step 2: Update Your Payment Details
Change the bank details on your invoices and payment platforms. Send recurring clients a short note with the new information. If you bill clients abroad, review how to receive international payments as a freelancer without losing money to fees.
Step 3: Move Business Subscriptions
Shift software, tools, and other recurring charges to your business debit card. Some freelancers also use virtual cards for freelancers to sort expenses by client or category.
Step 4: Pay Yourself Through an Owner’s Draw
Don’t spend directly from the business account on personal items. Instead, transfer money to your personal account. Record each transfer as an owner’s draw. This keeps your records clean and your separation clear.
Step 5: Connect Your Accounting Software
Link the new account to QuickBooks, Xero, or your bank’s built-in tools. Do it early, while your history is short and clean.
Step 6: Keep the Old Account Open Briefly
Some clients may keep paying the old account for a few weeks. Move those payments over as they arrive. Once all income flows to the new account, stop using the old one for business.
People Also Ask
Can freelancers use a personal bank account for business income?
Yes. Most sole proprietors can legally use a personal account for freelance income. But mixing funds makes taxes, bookkeeping, and financing harder over time. A separate account is usually the better long-term setup.
Is it illegal to deposit freelance income into a personal checking account?
No. For most sole proprietors, it’s legal. The risks are practical: harder documentation, higher prep fees, and messier records. Also check your bank’s terms, since some limit business use of personal accounts.
Does an LLC need a separate bank account?
No federal law requires it, but it’s strongly recommended. A separate account helps keep your LLC legally distinct from you. Without it, a court may find grounds for piercing the corporate veil.
Can I open a business bank account without an LLC?
Yes. Sole proprietors can usually open a business account with an SSN or EIN and a photo ID. If you operate under a business name, you may also need a DBA certificate.
Does a separate business account help in an IRS audit?
Yes. It makes it faster and easier to show which income and expenses belong to your business. It won’t prevent an audit. But it can make responding simpler and less expensive.
Do I need a 1099 to report freelance income?
No. All freelance income is taxable, regardless of whether you receive a Form 1099-NEC or 1099-K. Reporting thresholds have risen under recent law, but your obligation to report every dollar has not changed.
Are there business checking accounts for freelancers with no monthly fee?
Yes. Many online business bank accounts offer no-monthly-fee plans. Compare features like tax tools, deposit coverage, and transfer fees before you choose.
How should freelancers pay themselves from a business account?
Transfer money to your personal account and record it as an owner’s draw. Avoid paying personal bills straight from the business account. This keeps your records and your separation clean.
What is the best account setup for a freelancer just starting out?
If you’re just starting out, a personal checking account can work fine for very occasional side income with minimal transactions. But as soon as your freelance work becomes regular — or you start claiming deductions, using accounting software, or thinking about future growth — a separate business account is the better setup. It costs little to open, often nothing with a no-monthly-fee plan, and it prevents the bookkeeping cleanup and audit headaches that catch many freelancers off guard later.
What Emily Did Next
Emily opened a no-monthly-fee business account the week after her audit response. She moved every client payment there. She set aside a share of each payment for quarterly taxes.
The next year, her accountant’s fee dropped sharply. The records were already sorted. Later, she applied for a business line of credit. She handed the lender clean statements instead of a stack of explanations.
The account didn’t make Emily a better writer. It just stopped her finances from working against her.
Bottom Line: Which Account Should You Use?
A personal account is often legal for freelancers. It’s rarely the best long-term setup. A dedicated business account gives you cleaner records, easier bookkeeping, stronger deduction support, and better standing with lenders.
- Sole proprietors: You can use a personal account, but you’ll usually do better with a separate one once income is steady.
- LLC owners: Keep business and personal money fully separate to protect your liability shield.
- Growing freelancers: Start building clean business history now. You can’t create it later.
Your Transition Checklist
- Open a dedicated business checking account
- Update invoice and payment platform details
- Notify recurring clients of the new account
- Move subscriptions to your business debit card
- Pay yourself through owner’s draws
- Connect your accounting software
- Set aside money from each payment for quarterly estimated taxes
- Review the account monthly for stray personal charges
Ready to pick a provider? Explore more guides in our freelance banking hub.
Freelance Banking · Editorial Integrity
Sources & Citations
Official tax guidance, banking rules, business-structure resources, and current editorial research behind this guide to freelancer bank accounts, personal accounts, commingling risk, tax documentation, LLC separation, and lending readiness.
This guide is grounded in public government guidance, official tax resources, banking documentation, and legal reference materials relevant to freelancers and small business owners choosing between a personal and business bank account. We prioritized primary sources for tax reporting, recordkeeping, business structure, deposit protection, and lending context, then used them to explain how account separation affects deductions, bookkeeping, liability protection, and financing readiness. Because tax thresholds, banking features, and compliance requirements can change, readers should verify the latest rules and provider terms before making tax, legal, or financial decisions.
View full sources, methodology, and editorial notes
This article was developed using primary government materials, official tax guidance, business-structure resources, legal reference sources, and related editorial research relevant to freelancer banking. We favor official IRS, SBA, FDIC, and legal reference materials when explaining recordkeeping, Schedule C reporting, self-employment tax, home office deductions, business account setup, LLC separation, and lending readiness. Supporting internal references are included where they expand on a topic discussed in the guide. This article is educational information and should not be treated as tax, legal, financial, or compliance advice.
- Self-employed tax obligations and quarterly payments: IRS — Self-Employed Individuals Tax Center — cited for general tax obligations, estimated payments, self-employment tax, business structures, and home office deduction guidance relevant to freelancers.
- Business income and expense reporting: IRS — Schedule C (Form 1040) — cited for how sole proprietors report profit or loss from business activity and how Schedule C relates to freelance income and deductions.
- 1099 reporting and payment-form context: IRS — Form 1099-NEC and IRS — Understanding Your Form 1099-K — cited for current information on nonemployee compensation reporting and third-party network payment reporting.
- Employer Identification Number and business setup: IRS — Get an Employer Identification Number (EIN) — cited for official EIN application guidance relevant to freelancers and LLC owners opening business bank accounts.
- Deposit insurance and account protection: FDIC — Deposit Insurance — cited for the article’s explanation of deposit protection and the need to verify how account coverage works with different providers.
- Business structure and bank-account setup guidance: SBA — Choose a Business Structure and SBA — Open a Business Bank Account — cited for business-structure context, legal separation, and practical business banking guidance for small business owners.
- Legal reference on veil piercing and entity separation: Cornell Law School — Piercing the Corporate Veil — cited for general legal context on why LLC owners should keep business and personal finances separate.
- Related internal guide on freelancer banking decisions: Tech Capital Hub — Best Digital Banking Apps for Freelancers — cited as a relevant internal resource for comparing business account options once readers decide to separate freelance and personal finances.
- Related internal guide on entity-based account setup: Tech Capital Hub — Sole Proprietor vs LLC Bank Accounts — cited as a supporting internal source for LLC banking requirements, entity separation, and documentation differences.
- Related internal guide on account-opening requirements: Tech Capital Hub — Documents Needed to Open a Business Bank Account — cited as a supporting internal resource for the practical setup steps discussed in the article.
Freelance Banking · Editorial Standards
Our Editorial Standards
Tech Capital Hub applies Google’s E-E-A-T framework to every freelancer banking and business finance guide, with a focus on practical clarity, official documentation, and verifiable sources over generic advice or unsupported claims. This article draws on trusted primary and legal-reference materials where they support specific points — including IRS guidance for self-employed tax obligations, Schedule C reporting, recordkeeping, home office deductions, and EIN setup; SBA materials for business-structure and business-bank-account guidance; FDIC resources for deposit protection; and Cornell Law’s legal reference material for general context around piercing the corporate veil. Where provider terms, tax thresholds, or compliance expectations can change, we frame the information carefully and encourage readers to verify the latest rules directly.
View how our editorial standards apply to this article
Written for Working Freelancers and Solo Business Owners
This article is built for people making real decisions about where freelance income should land, how business expenses should be tracked, and when a separate account becomes necessary. Instead of speaking in abstract tax or banking language, it explains how personal and business accounts affect everyday operations like invoicing, bookkeeping cleanup, documentation, and preparing for tax season.
Complex Banking, Tax, and LLC Topics Explained Clearly
The guide breaks down difficult but important concepts — including commingling, Schedule C reporting, self-employment tax, owner’s draws, LLC separation, and debt-service coverage ratio — into plain language without losing accuracy. It distinguishes between what is legally allowed, what is operationally smart, and what becomes risky as a freelance business grows.
Primary Sources First, Supporting Internal Guides Second
Specific claims are anchored to official and recognizable sources wherever possible. IRS materials support the article’s discussion of recordkeeping, estimated taxes, home office deductions, and payment reporting. SBA guidance supports business-structure and bank-account setup context. FDIC materials support deposit-protection explanations. Internal Tech Capital Hub articles are linked only where they deepen a related topic already introduced in the guide.
Clear About Limits, Risk, and Changing Rules
Freelancer banking advice can drift into oversimplification. This guide avoids that. It does not present educational content as tax or legal advice, does not promise outcomes, and does not treat changing thresholds or provider features as fixed forever. Where the article discusses reporting rules, lender expectations, or account protections, it encourages readers to verify the latest official guidance and provider disclosures before acting. Corrections or source questions can be sent to the editorial team.
Freelance Banking · About the Author
James Whitfield
Senior Fintech Editor & Analyst · Tech Capital Hub
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering digital banking, payments, and compliance for freelancers and small businesses. In this guide, he explains when freelancers can use a personal checking account, when a business account makes more sense, and how account structure affects taxes, bookkeeping, legal separation, and financing.
View full author bio, credentials, and links
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering digital banking, payments, and compliance for freelancers and small businesses. He writes for independent professionals, sole proprietors, and growing business owners who need practical guidance on how financial systems work in real life, not just in theory.
His reporting focuses on the operational side of modern business banking: how freelancers set up and use bank accounts, how account structure affects tax documentation and bookkeeping, how LLC owners protect legal separation, and how clean financial records improve financing readiness. For this article, James explains the tradeoffs between using a personal checking account and a business account, clarifies what is legally allowed versus operationally smart, and grounds the discussion in public guidance, compliance context, and real-world workflow considerations. All articles are educational information and should not be treated as tax, legal, or financial advice.
- Covers freelancer banking, business checking, and compliance topics through the lens of real operational use
- Explains tax documentation, account separation, bookkeeping systems, and LLC banking in plain language
- Tracks how digital banking tools, payment workflows, and account structures affect solo business owners in practice
- Separates what is legally permitted from what is financially or operationally smartest for growing freelancers
- Grounds analysis in public guidance, named sources, and clear editorial standards with educational framing
Enjoying our content?
Click below to add us as a preferred source. Google will prioritize our latest articles in your Top Stories, AI Mode, and AI Overviews.
Preferred Source on Google