How to Automate a 13-Week Cash Flow Forecast With AI: A Step-by-Step Guide
Fintech Analyst · Founder of Tech Capital Hub
Marcus has spent more than a decade researching AI-powered treasury forecasting for finance teams. In this guide, he walks through how to automate a 13-week cash flow forecast — building rolling cash flow models on live data, connecting ERP and bank APIs, and strengthening liquidity management for mid-market and enterprise teams instead of trusting stale batch exports.
I spent three years building 13-week cash flow forecasts by hand. Every Monday, without fail — pull the ERP export, clean it, paste it into the model, add bank balances manually because the bank portal doesn’t talk to anything, adjust AR assumptions based on Friday’s collections calls, send it by 9am. Then, around week 6 or 7, something would come in off by enough to matter. A late payment. A dispute nobody logged. A wire that cleared over the weekend but wasn’t in Monday’s export yet.
If you’re building a 13-week cash flow forecast by hand right now, that story probably sounds familiar. Here’s the direct answer before we get into the how-to: manual 13-week forecasts average around 60% accuracy, while AI-driven models on the same horizon reach 88 to 92%, according to treasury research synthesized across global practitioners and cited throughout our companion guide below. That’s not a rounding error — it’s the difference between guessing and knowing. This guide walks through exactly how to close that gap, step by step, using real infrastructure rather than vendor promises.
For the broader context on why forecast accuracy has become such a pressing issue for treasury teams in 2026, our complete guide to AI cash flow forecasting covers the market shift, the accuracy data by horizon, and the platform landscape in more depth. This piece is the tactical follow-up — the actual build.
Key Takeaways
- Manual 13-week cash flow forecasts average roughly 60% accuracy; AI-driven models on the same horizon reach 88–92%, mainly because they use live data and invoice-level prediction instead of stale batch exports and segment averages.
- Data cleanup is the single most important — and most skipped — phase of implementation. Budget four to eight weeks for it before touching any platform.
- A 13-week cash flow model isn’t one algorithm; it’s a stack of specialized agents (collection prediction, payment timing, scenario, variance alert) each running on different data.
- Governance isn’t optional anymore. The NIST AI Risk Management Framework, the Colorado AI Act, and Texas TRAIGA all touch AI-driven liquidity forecasting directly.
- Track three numbers in the first 90 days — MAPE improvement, forecast build time, and DSO/DPO movement — to know whether the automation is actually working.
What Is a 13-Week Cash Flow Forecast?
A 13-week cash flow forecast is a rolling, 90-day projection of weekly cash coming in and going out. It’s the standard tool for short-term liquidity management, and it sits in a specific gap: daily positioning is too reactive to plan around, and annual budgets are too abstract to inform this week’s decisions. The 13-week window is where actual funding decisions — credit line draws, vendor payment timing, covenant headroom — get made.
If you’re researching how to build a 13 week cash flow model for the first time, know this up front: the model itself is simple in concept (weekly buckets of receipts and disbursements, rolling forward each week) but the accuracy depends entirely on the freshness and granularity of what feeds it. That’s the part this guide is really about.
A 13 week cash flow forecast for a private equity firm monitoring a portfolio company works the same way structurally, but the stakes are different — it’s often the earliest, clearest signal of liquidity trouble in a deal that quarterly financials won’t surface for months. We cover that use case directly in the FAQ section below.
Table of Contents
Why the 13-Week Window? (Rolling vs. Static Cash Flow Forecast)
Daily forecasts are too noisy for planning, and monthly forecasts are too slow to catch a liquidity problem before it becomes urgent. Thirteen weeks — one quarter, broken into weekly buckets — gives you enough resolution to see what’s actually moving and enough runway to act before a small problem becomes a real one.
I get asked this constantly, usually by people who lean toward daily rolling forecasts or monthly variance reviews instead. Daily forecasts are too noisy — you end up chasing clearing differences and timing quirks that net out by Thursday anyway. Monthly forecasts are too slow if you’re staring down a possible covenant breach; you need visibility in week 4, not at month-end close.
A rolling 13-week forecast — updated every week, always looking 13 weeks forward — beats a static one built once per quarter, because it never goes stale. It’s also the horizon where AI’s accuracy advantage is most dramatic: manual sits at 60%, AI-driven models hit 88 to 92%. That 30-point gap changes what a treasury team can responsibly commit to in a board meeting.
Why Manual Forecasting Fails (and What AI Fixes)
Manual forecasting isn’t failing because your team is careless. It’s failing structurally, because a standard ERP snapshot is typically three to seven days old by the time it lands in a model — and real things happen in those days.
Invoices get disputed, customers negotiate extensions, and payments clear that “should” still be outstanding. Your spreadsheet has none of that. It’s predicting the past.
AI doesn’t just speed up the old process — it replaces the input layer entirely. Real-time bank and ERP feeds, invoice-level payment prediction instead of segment averages, and continuously learning models close the structural gap that no amount of manual diligence can fix. Here’s exactly how to build that, step by step.
Step 1: Clean and Standardize Your Data Before Anything Else
Do this before connecting any platform: audit your AR aging for live dispute status, document where every input comes from, and consolidate AR, AP, payroll, and bank data into one consistent feed. Budget four to eight weeks for this phase — it’s the step every rushed implementation regrets skipping.
Nobody wants to hear this, and I didn’t want to hear it the first time either. There’s a real temptation to buy a platform, connect it, and expect the magic to start immediately. The vendors are convincing. But the honest ones will tell you the same thing: the model is only as good as what you feed it.
A forecasting model running on dirty data doesn’t produce messy output — it produces confident, clean-looking forecasts that are simply wrong. That’s worse than a shaky spreadsheet, because at least the spreadsheet looks unreliable.
Before logging into anything:
- Audit your AR aging report properly. Is dispute status live, or is this a snapshot from last night’s batch job? For a deeper look at what “AR-ready” data actually looks like, our breakdown of AI accounts receivable automation tools covers the mechanics of matched payments, dispute flags, and promise-to-pay data in detail.
- Document your data lineage. For every major input — AR, AP, payroll, bank balances — know where it comes from, how fresh it is, and how often it updates.
- Establish one source of truth. At most mid-market companies, AR lives in one system, AP in another, payroll exports from a third, and bank balances get typed in manually on Monday morning. AI needs one consistent feed, not four disconnected ones.
Teams that rush this phase don’t save time — they spend the same time fixing problems after go-live, under more pressure.
Step 2: Replace Batch Exports With Live ERP and Bank API Connections
Live API connections close the lag that batch exports create. NetSuite, SAP, and Oracle all support REST APIs that push AR aging, open invoices, and purchase orders continuously, while direct bank APIs or SWIFT MT940 feeds replace manual statement downloads for live cash positions across every account.
Batch exports are popular because they’re easy — scheduled, automated, reliable. The problem is what they miss. A wire that clears Saturday night isn’t in Monday’s ERP export. A dispute opened at 8am won’t show until tonight’s batch. By the time your forecast reflects reality, reality has already moved on.
Connecting these APIs cleanly is trickier than most vendor demos suggest; our guide to integrating AI forecasting with your ERP goes deep on the specific pitfalls, including the multi-entity consolidation errors that quietly inflate a forecast.
This matters more than it sounds — every week’s forecast inherits from the prior week’s opening balance. If week one is off by $200K, that error compounds through all 13 weeks.
One standard worth knowing here: ISO 20022. It’s a messaging format for financial data exchange, and what makes it useful for forecasting is that it carries metadata — not just “payment moved” but which invoice, which entity, what the relationship is. According to the official ISO 20022 standard documentation, this structured data enables far more precise transaction categorization than older formats, which is a big part of why AI systems built on ISO 20022 data significantly outperform those working from legacy payment messages.
Step 3: Let the Machine Learning Cash Flow Model Run Before You Trust It
Run your new AI model in parallel with your existing manual model for four to six weeks before switching over. Every serious forecasting platform needs a 30- to 60-day learning period to backtest against historical data and match each cash flow category to the right modeling approach.
This is where most teams stumble. They connect the data, flip the switch, and immediately abandon their manual model. Two weeks later, something looks off, and the whole team decides the AI “doesn’t work.”
Here’s what that learning period actually does: fixed payments like rent get a simple straight-line model. Payroll might need an LSTM (Long Short-Term Memory, a deep learning approach built for time-series data) because timing shifts with headcount and calendar. A large customer’s AR might need a Transformer model if their payment behavior tracks something like freight costs or their own inventory cycles.
None of this needs manual configuration — but it needs the time. That side-by-side comparison also builds trust with your team; nobody trusts a black box, but people trust something they’ve watched be right for six straight weeks.
Step 4: Understand What’s Actually Running Under the Hood (AI Agent Types)
A 13-week cash flow model isn’t one algorithm. It’s a stack of specialized agents, each assigned to a different category of cash flow:
- Collection prediction agents work at the individual invoice level, not segment averages. A customer with two years of on-time history gets a 95% payment probability; one with three recent disputes gets 60% and a 45-day window — even though both show as simply “outstanding” in your AR aging. For a detailed look at how this pattern recognition works, see our guide on predicting late payments and fixing accounts receivable.
- Payment timing agents handle the AP side — deciding when to pay each vendor to capture early discounts without straining cash at a bad moment.
- Scenario agents model “what if” situations — a stretched customer, a freight cost spike, accelerated collections on the top 20 accounts — in minutes instead of days.
- Variance alert agents monitor actuals against forecast and flag deviations, distinguishing a timing issue (money’s still coming) from a real loss.
These agents update independently. A dispute on your largest customer updates the collection agent instantly, while the payment timing agent keeps running on whatever AP data it already has. The forecast is always working from the freshest version of each data type it tracks.
Step 5: Build In Scenario Stress Testing
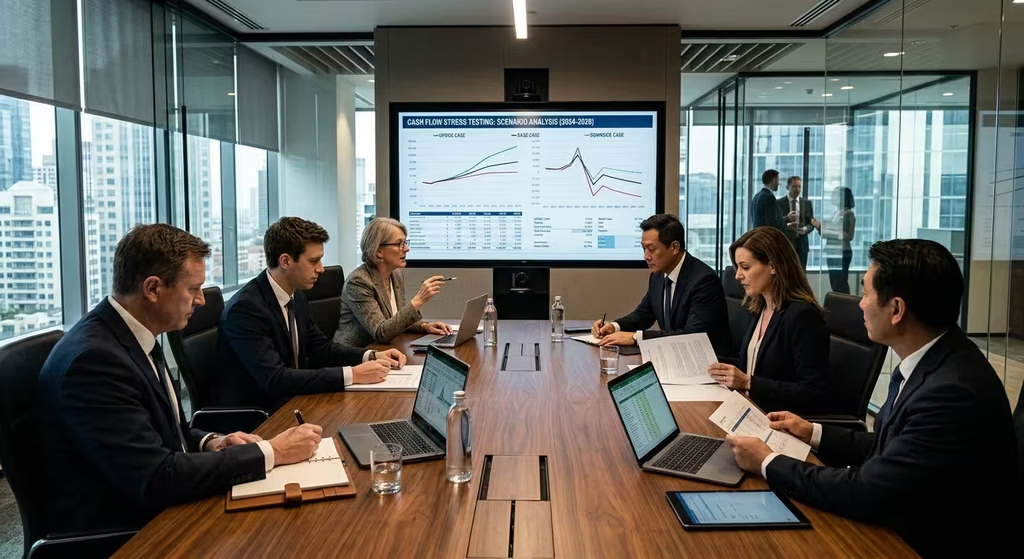
AI replaces the single-column forecast with a full probability distribution. Monte Carlo simulation runs thousands of variations across payment timing, rates, and operational assumptions to show a median outcome, a downside scenario, and tail risk — all in one view.
A traditional 13-week forecast gives you one number per week — one column. You build it, present it, and find out later whether you were right. That single-point estimate is genuinely useless in a board conversation about covenant headroom.
The stronger platforms also support action-linked simulation: specify a decision (accelerate collections on the top 20 accounts by a week, defer three vendor payments) and the model shows the effect across the full 13-week horizon.
Step 6: Switch to Exception-Based Cash Management
Once the model is calibrated, your team’s job stops being “build the forecast every Monday” and becomes “review what the system flagged and decide whether the flag is right.” Deviations above your threshold get surfaced automatically; everything below it, the model just handles.
The organizational effect is real. Companies that make this shift report meaningfully higher engagement in finance roles and lower turnover — largely because the work gets more interesting. The skill that matters now isn’t building the spreadsheet; it’s knowing when the model is wrong because something is happening at the business level that isn’t in the data yet.
Step 7: Governance and Compliance (NIST AI RMF, Colorado AI Act, Texas TRAIGA)
Governance sounds boring until your CFO asks why the model recommended drawing on a credit line, and “the algorithm said so” ends the conversation badly.
The U.S. Treasury’s Financial Services AI Risk Management Framework — built on the NIST AI Risk Management Framework — covers 230 control objectives across the AI lifecycle, from procurement through ongoing monitoring. The Colorado AI Act requires impact assessments for AI systems making high-risk financial decisions, and liquidity forecasting qualifies. Texas TRAIGA requires disclosure when counterparties are interacting with AI agents. None of this is hypothetical or far-off.
Build a reasoning chain that’s visible on demand: which inputs drove a recommendation, what probability threshold triggered it, what assumptions the model made. One detail most teams miss: the “right to unlearn.” Emerging regulations require that when sensitive data is deleted from your systems, it also gets removed from model weights — not just the database. Your data governance policy needs to cover model retraining, not just storage.
Best Cash Flow Forecasting Software: Platform Comparison Table
No paid placements here — this is based on published specs and independent research, not vendor briefings.
Comparison Table
Best Cash Flow Forecasting Software: Platform Comparison Table
Compare leading cash flow forecasting platforms by best-fit use case, core strength, and typical implementation timeline.
Transformance
Mid-marketBest for: AR-heavy mid-market companies
Standout strength: Forecasts from processed AR data, including matched payments, active disputes, and promise-to-pay signals rather than raw ERP extracts.
Implementation time: 4–8 weeks
HighRadius
EnterpriseBest for: Large enterprises with complex AR
Standout strength: 100+ machine learning models, specialized agents, and end-to-end automation.
Implementation time: 3–6 months
Trovata
Fast rolloutBest for: Upper-mid-market teams needing speed
Standout strength: Direct bank API streaming and NLP search for faster adoption.
Implementation time: 1–3 months
Kyriba
Global treasuryBest for: Multi-currency, multi-bank enterprises
Standout strength: Strong bank connectivity at scale with FX hedging capabilities.
Implementation time: Varies by scope
Cube
Excel-friendlyBest for: Excel-native teams not ready to leave spreadsheets
Standout strength: Real-time GL integration with a practical migration on-ramp.
Implementation time: 2–4 weeks
| Platform | Best For | Standout Strength | Implementation Time |
|---|---|---|---|
| Transformance | AR-heavy mid-market companies | Forecasts from processed AR data — matched payments, active disputes, and promise-to-pay signals rather than raw ERP extracts | 4–8 weeks |
| HighRadius | Large enterprises with complex AR | 100+ machine learning models, specialized agents, and end-to-end automation | 3–6 months |
| Trovata | Upper-mid-market teams needing speed | Direct bank API streaming and NLP search for faster adoption | 1–3 months |
| Kyriba | Multi-currency, multi-bank enterprises | Strong bank connectivity at scale with FX hedging capabilities | Varies by scope |
| Cube | Excel-native teams not ready to leave spreadsheets | Real-time GL integration with a practical migration on-ramp | 2–4 weeks |
Match the tool to your actual bottleneck. The platform that fits a Fortune 500 treasury team with 40 banking relationships will likely overwhelm a $75M company running NetSuite — and vice versa, a lightweight tool won’t hold up at enterprise scale.
For companies deciding between building on top of existing AP/AR tooling versus a dedicated forecasting layer, our comparison of AI invoicing software tools is a useful companion read, since invoice-level data quality feeds directly into forecast accuracy.
How to Know If It’s Working (MAPE, DSO, DPO KPIs)
Watch three numbers in the first 90 days: MAPE improvement at the 13-week horizon, forecast build time, and DSO/DPO movement. If any of the three don’t move, the problem is almost always in the data layer, not the model settings.
- MAPE improvement at the 13-week horizon. MAPE (Mean Absolute Percentage Error) is the standard forecast-accuracy metric. Target 28 to 32 percentage points of accuracy gain. If you’re not seeing that by week 12, the data foundation likely has a problem, or the learning period was cut short.
- Forecast build time. Should drop from three to four hours per week to under 15 minutes. If it hasn’t, something is still being manually prepped somewhere upstream.
- DSO and DPO movement. Days Sales Outstanding and Days Payable Outstanding should improve by two to four days within 90 days — real working capital freed up by better prediction, not by squeezing vendors.
If any of these three don’t move, resist the urge to tweak model settings. Go back to the data layer first — that’s almost always where the real problem lives.
People Also Ask
What is a 13-week cash flow forecast used for?
It’s used for short-term liquidity management — deciding whether to draw on credit lines, when to pay vendors, and whether covenant headroom is real. It sits between daily cash positioning, which is too reactive, and annual budgeting, which is too abstract for near-term decisions.
How does AI actually improve 13-week forecast accuracy?
Two mechanisms do most of the work: real-time data replacing batched exports, and invoice-level payment prediction replacing segment-level averages. Fixing data freshness alone gets partial improvement; combining it with granular prediction is what moves accuracy from roughly 60% to 88–92%.
How long does it take to build a 13 week cash flow model with AI?
Realistically, three to six months end-to-end: four to eight weeks of data cleanup, followed by live API integration running in parallel, a 30- to 60-day model learning period, and a phased shift to exception-based management. Skipping any of these steps to “go live” faster typically adds months later, not saves them.
Is a 13 week cash flow forecast useful for a private equity firm evaluating a portfolio company?
Yes — arguably more than most other forecasting tools. A 13 week cash flow forecast for a private equity firm doing diligence or active portfolio monitoring reveals near-term liquidity risk that quarterly financials can hide entirely, especially for companies with seasonal AR patterns or thin covenant headroom.
What’s the biggest reason these AI forecasting implementations fail?
Almost always the same root cause: data problems that weren’t fixed before go-live. Skipping the parallel-running period, having no clear owner for exception review, and underestimating governance requirements are the next most common failure points.
Is a spreadsheet ever good enough for a 13 week cash flow model, or do I need dedicated software?
A spreadsheet can work for a single-entity company with clean, consistent categorization and a small AR portfolio. Once you’re managing multiple entities, hundreds of open invoices, or several banking relationships, the manual reconciliation burden and 60% average accuracy ceiling make dedicated AI-driven software worth the switch.
How often should a rolling 13-week cash flow forecast actually be updated?
Weekly, at minimum, so it always looks 13 weeks forward from the current date rather than from whenever it was last built. AI-driven platforms update continuously as new bank and ERP data arrives, which is a large part of why they outperform a forecast refreshed once a quarter.
What This Actually Changes
A 13-week forecast running at 90% accuracy isn’t a marginal upgrade from 60% — it changes what you can say in a board meeting. A CFO with a real probability distribution doesn’t present a single number and hope for the best; she presents a range, explains the conditions behind it, and answers the hard questions before anyone has to ask twice.
None of this is painless. The data cleanup is genuinely slow. The parallel-running period demands patience most teams don’t budget for. Governance takes longer than anyone plans. This is real work, not a weekend project.
But if your forecast keeps missing — and you’ve already cleaned the data, updated the methodology, and added detail to the model — the spreadsheet probably isn’t the problem anymore. Something underneath it is. Start with Step 1, be honest about your data, and the rest of this actually gets easier from there.
Disclaimer: Informational only. Not financial, legal, or investment advice. Accuracy figures are drawn from published treasury research and vendor documentation. Your results will depend on your data quality, implementation choices, and business context. Evaluate any platform against your own requirements first.
AIFinOps · Editorial Integrity
Sources & Citations
The official frameworks, messaging standards, and regulatory guidance behind this step-by-step guide to automating a 13-week cash flow forecast with AI — covering data integration, ML forecasting, scenario stress testing, and AI governance for treasury teams.
Every claim in this guide is anchored to official standards, regulatory frameworks, and independent treasury research! Data integration points reference the ISO 20022 messaging standard and SWIFT MT940 statement formats, while the AI governance and compliance guidance draws on the NIST AI Risk Management Framework, the Colorado AI Act, and the Texas Responsible AI Governance Act (TRAIGA). Accuracy ranges and implementation timelines reflect published treasury research and vendor documentation. Because regulations, platform features, and benchmark figures change fast, always verify the latest details with each provider and a licensed advisor before you act on them!
View full sources, methodology, and editorial notes
This guide was built from official messaging standards, primary regulatory and framework text, dated treasury research, and hands-on review of real forecasting and scenario-modeling workflows. We give preference to primary standards, government frameworks, and official documentation wherever they directly support a claim about data integration, model governance, or how a 13-week cash flow forecast actually works. A few figures — like accuracy ranges and DSO/DPO gains — are described as reported ranges drawn from published treasury research and vendor documentation, since results vary by data quality and implementation. This article is educational information, not licensed financial, legal, or investment advice — always confirm framework applicability, platform features, and regulatory obligations with each provider and your own advisor.
- AI risk management and governance framework: NIST — AI Risk Management Framework (AI RMF 1.0) — cited as the foundational, voluntary US framework for governing AI systems across the Govern, Map, Measure, and Manage functions, directly relevant to AI-driven liquidity forecasting.
- Financial messaging and transaction data standard: ISO 20022 — Universal Financial Industry Message Scheme — cited as the structured messaging standard whose rich metadata enables far more precise transaction categorization than legacy payment formats.
- Bank statement messaging format: SWIFT — MT940 Customer Statement Message — cited for the standardized end-of-day bank statement format used to feed live cash positions into a forecasting model.
- State AI governance legislation (Colorado): Colorado General Assembly — SB24-205, Colorado Artificial Intelligence Act — cited for impact-assessment requirements applying to AI systems that make high-risk financial decisions, including liquidity forecasting.
- State AI governance legislation (Texas): Texas Legislature — HB 149, Texas Responsible Artificial Intelligence Governance Act (TRAIGA) — cited for disclosure requirements when counterparties are interacting with AI agents.
- Enterprise ERP integration documentation: Oracle NetSuite — SuiteTalk REST Web Services Documentation — cited for the REST API capabilities that push AR aging, open invoices, and purchase orders continuously into a forecasting layer.
13-Week Cash Flow Forecasting · Editorial Standards
Our Editorial Standards
Tech Capital Hub applies Google’s E-E-A-T framework to every guide on automating a 13-week cash flow forecast with AI, favoring hands-on testing, official standards, and dated treasury research over hype or unsupported claims. This guide anchors specific points to trusted references — the NIST AI Risk Management Framework for model governance, the ISO 20022 messaging standard and SWIFT MT940 statement format for data integration, and the Colorado AI Act and Texas TRAIGA for regulatory disclosure. Accuracy ranges and implementation timelines reflect published treasury research and vendor documentation. Because regulations, platform features, and benchmark figures change fast, we describe the general 2026 picture rather than overstate certainty!
View how our editorial standards apply to this article
Built on Hands-On Forecasting Platform Testing
This guide is grounded in real, hands-on work — not theory. We reviewed treasury forecasting platforms like Transformance, HighRadius, Trovata, Kyriba, and Cube across the workflows that actually matter, from connecting ERP and bank APIs to building a rolling 13-week model and running it in parallel with a manual forecast. Everyday framing anchors the lessons — why a stale Monday-morning export predicts the past, how a single missed wire compounds across all 13 weeks — so the ideas genuinely stick for finance teams making real funding decisions.
13-Week Forecasting Concepts, Minus the Jargon
Coverage breaks down the concepts that shape an accurate forecast. We clarify how a rolling forecast beats a static one, why MAPE is the accuracy metric that matters, how exception-based cash management changes the team’s job, and how Monte Carlo stress testing turns a single number into a real probability range. Every term — MAPE, DSO, DPO, the collection and payment-timing agents behind the model — is defined in plain language before it’s used.
Official Standards and Frameworks Where They Fit
Specific claims are anchored to trusted references. Model governance and compliance points draw on the NIST AI Risk Management Framework, the Colorado AI Act, and the Texas Responsible AI Governance Act (TRAIGA), while data integration points reference the ISO 20022 messaging standard and the SWIFT MT940 statement format. Accuracy and implementation figures reflect published treasury research and vendor documentation. We avoid promotional content and unverified numbers as support for any point.
Honest About Trade-offs, Tools, and Updates
We state the hard truths as plainly as the mechanics: no single platform wins for every team, a model is only as good as the data feeding it, and platform features and AI regulations change often — so verify current details and your own compliance obligations before you commit. This guide is reviewed and updated as frameworks and provider documentation shift. Nothing here is licensed financial, legal, or investment advice; always confirm decisions with your own accountant or advisor. Corrections or source challenges can be sent to editorial@techcapitalhub.com.
13-Week Cash Flow Forecasting & Treasury Automation · About the Author
Marcus Delray
Fintech Analyst · Founder of Tech Capital Hub
Marcus Delray is a fintech analyst and the founder of Tech Capital Hub. In this guide, he shows you exactly how to automate a 13-week cash flow forecast with AI — connecting ERP and bank APIs, building a rolling cash flow model on live data instead of stale exports, and sharpening liquidity management for mid-market and enterprise treasury teams. His focus is on clear, practical steps you can actually follow, not hype!
View full author bio, credentials, and links
Marcus Delray has spent over a decade researching financial technology. He built Tech Capital Hub to make that research genuinely useful for finance leaders — from mid-market treasury teams modernizing their first automated forecast to enterprise groups managing dozens of banking relationships across multiple entities. He covers AI-powered treasury forecasting, liquidity management, and FinOps tools, with a consistent focus on turning stale, disconnected data into a clear, reliable picture of a company’s near-term cash position.
For this guide, Marcus answers a question most finance teams get wrong until a forecast misses at the worst possible moment: why does the number keep drifting off? He reviewed treasury forecasting platforms hands-on — Transformance, HighRadius, Trovata, Kyriba, and Cube — across the workflows that matter, from connecting ERP and bank APIs to building a rolling 13-week model and running it in parallel with a manual one. He walks through each step of the build, explains why a rolling forecast beats a static quarterly one, and shows how exception-based cash management frees a team to focus on the flags that actually matter.
His work draws on the NIST AI Risk Management Framework for model governance, the ISO 20022 messaging standard and SWIFT MT940 statement format for clean data integration, and dated treasury research for accuracy and implementation ranges. Where figures shift by data quality and setup, he describes the general picture rather than overstate certainty. All articles are educational information, not financial advice.
- Explains why a rolling 13-week cash flow forecast beats a static quarterly one — always looking 13 weeks forward so it never goes stale
- Breaks down live ERP and bank API integration, from REST feeds that push AR aging and open invoices to SWIFT MT940 statements that keep cash positions current
- Clarifies AI model governance in plain terms, grounded in the NIST AI Risk Management Framework across the Govern, Map, Measure, and Manage functions
- Shows how to track the KPIs that prove automation is working — MAPE accuracy gains at the 13-week horizon, faster forecast build time, and real DSO/DPO improvement
- Grounds coverage in official standards like the NIST AI RMF and ISO 20022, plus dated treasury research, with clear educational framing and no financial advice
Enjoying our content?
Click below to add us as a preferred source. Google will prioritize our latest articles in your Top Stories, AI Mode, and AI Overviews.
Preferred Source on Google