AI in Digital Banking: How Your Bank Uses AI (and What It Means for You)
Senior Fintech Editor & Analyst · Tech Capital Hub
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering AI, digital banking, and payment infrastructure. In this guide, he breaks down how banks and neobanks are using AI today, from fraud detection and KYC automation to personalized banking, and what it means for everyday account holders.
Quick answer: AI digital banking uses machine learning to detect fraud, predict overdrafts, speed up disputes, automate identity checks, and personalize account insights. In 2026, most major banks and top neobanks already run these systems behind the scenes. The benefits are real, but so are the limits around transparency, oversight, and credit decisions.
For the bigger picture on where this fits, see our pillar guide on fintech trends in 2026.
Your bank is already using AI to manage your money. It flags odd transactions, predicts overdrafts, and sometimes helps decide whether you qualify for credit. Most of the time, no one tells you.
This guide explains what smart banking technology actually means for you. You’ll learn how banks and neobanks use AI today, where it helps, where the real risks sit, and the exact questions to ask before trusting an AI-driven banking feature.
Here’s what’s inside:
- How banks and neobanks use AI right now
- The best neobanks using AI for personal finance
- What to watch for before you trust these tools
- A quick FAQ and a clear next step
Key Takeaways
- AI in digital banking is mostly invisible. You feel it in faster approvals and better fraud catches, not in a flashy new button.
- Neobanks move faster than big banks. They ship AI features in weeks because they started on modern systems.
- Personalized banking is the new normal. Good apps now warn you before problems happen, not after.
- AI may influence your credit. That makes transparency and human review more important than ever.
- Trust signals matter. Look for banks that explain AI decisions and offer a human to talk to.
Table of Contents
How Has Technology Changed the Banking Industry?
Not long ago, banking meant branches, paper forms, and waiting days for a decision. Smart banking technology changed all of that.
Today, banking automation handles tasks that once required entire back-office teams. Payments get routed. Identities get verified. Risks get scored. Most of it runs in seconds, without a human in the loop.
The shift didn’t happen overnight. It started with online portals, moved to mobile apps, and has now landed firmly in AI. The most effective AI for online banking today doesn’t just automate old tasks — it creates new ones that were never possible before, like warning you about an overdraft before it happens or spotting a fraudulent charge before your card gets declined.
Mini takeaway: Banking automation didn’t replace banking. It made it faster, quieter, and in many cases smarter — for better and for worse.
What Is AI in Digital Banking?
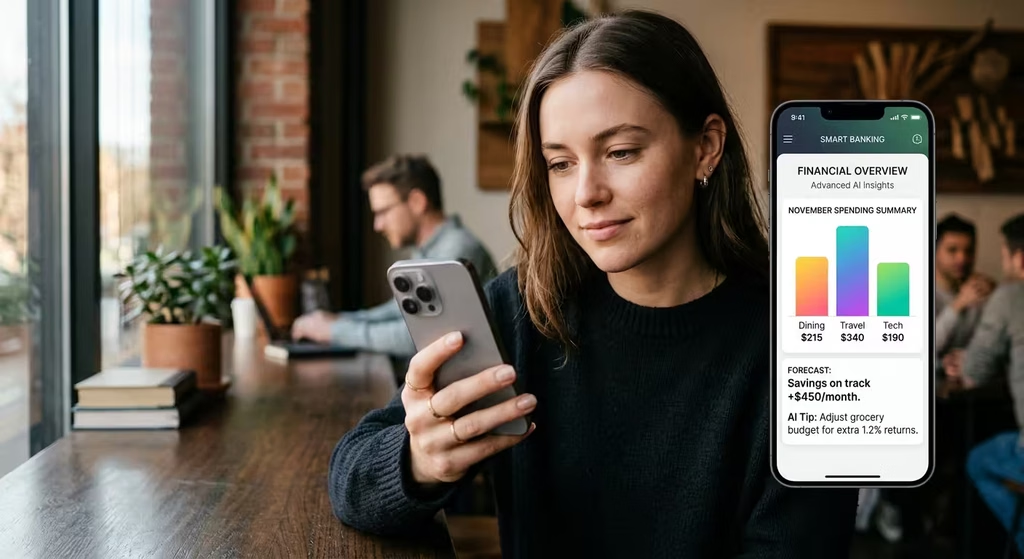
AI in digital banking means using machine learning to run everyday banking tasks. This includes fraud checks, overdraft alerts, dispute handling, identity verification, and personalized nudges.
It’s different from a basic chatbot. Chatbot banking follows a script and can’t reason. Modern AI studies your full account history and behavior. It acts before you ask, and it adapts to your habits.
Think of it this way. The old model was reactive. You checked your balance after you spent. The new model is predictive. Your app warns you about an overdraft before it hits.
Mini takeaway: When people say “AI in digital banking,” they usually mean smarter decisions running quietly in the background — not a robot answering your emails.
How AI Is Transforming Digital Banking Experiences
AI has moved from back-office automation to tools you touch every day. Here’s where you notice it most.
Faster, Smarter Customer Support Through Conversational Banking
Support used to mean waiting on hold. Now AI handles routine questions and disputes in minutes through what’s often called conversational banking — an online banking AI assistant that can understand your question, pull your account data, and resolve common issues without transferring you to a queue.
The value isn’t the AI itself. It’s the timing. A useful alert before a problem gets worse beats a long feature list.
Personalized Banking That Acts Early
Personalized banking is the biggest shift for account holders. Instead of generic emails, your app tailors insights to your actual behavior.
It can suggest a transfer when savings dip. It can flag a subscription you forgot. Done well, this cuts stress. Done poorly, it’s just noise.
Generative AI in Banking
Generative AI is starting to appear inside banking apps too. Some banks now use it to summarize spending patterns, draft dispute letters, or explain a fee in plain language. This is still early, but the direction is clear: the online banking AI assistant of 2026 will do far more than answer FAQs.
Intelligent Automation in Banking: The Systems You Never See
Most AI in banking is invisible. It scores risk, routes payments, and verifies documents. You never see the model. You just feel the result when your card clears or a bad charge gets blocked. This is intelligent automation in banking at scale — running across millions of accounts simultaneously, in milliseconds.
For a deeper look at the forces driving this, our guide on fintech trends in 2026 breaks down the full picture.
Best Neobanks Using AI for Personal Finance
Traditional banks have the money. AI neobanks have the speed. Because they started on cloud systems, they ship new features fast. This is also why banking automation trends are moving faster at neobanks — they aren’t slowed down by legacy infrastructure.
Here’s how a few leading neobanks use AI today.
AI in Digital Banking · Comparison
Best Neobanks Using AI for Personal Finance
Each of these neobanks leans on AI in a different way. Compare their standout features side by side and see which one fits how you actually manage money.
| Neobank | Key AI Feature | Best For |
|---|---|---|
| Chime | AI handles a large share of support, so disputes get resolved faster. | Primary checking and quick dispute resolution. |
| Monzo | Tax tools built for freelancers and sole traders. | Side hustlers, gig workers, and the self-employed. |
| Starling | A scam-check tool that reviews suspicious messages. | Fraud-conscious users who want an extra safety layer. |
| Revolut | A financial companion with proactive budgeting nudges. | Active planners and frequent travelers. |
A quick note on reading this table: “Best for” depends on your needs, not on hype. A freelancer may value tax tools, while a frequent traveler may value proactive alerts.
A quick note on reading this table. “Best for” depends on your needs, not on hype. A freelancer may value tax tools. A frequent traveler may value proactive alerts.
What an Artificial Intelligence Bank Account Feels Like in Practice
An AI neobank account tends to feel more hands-on. It nudges you before you overspend. It resolves disputes faster. It learns your routine and adapts.
That convenience is real. But it also means more of your data flows through automated systems. That’s where smart questions matter, which we’ll cover below.
Where AI Actually Helps You
Let’s get specific. These are the wins that matter for everyday users.
- Faster dispute resolution. Less time on hold, quicker refunds.
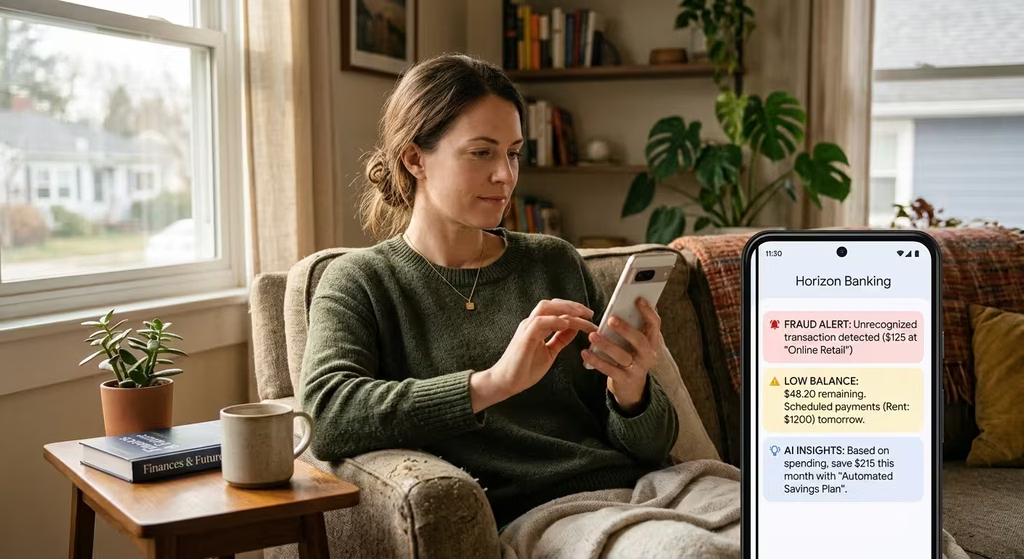
- Better fraud catches. Fraud detection AI learns your patterns and flags what doesn’t fit.
- Quicker account opening. KYC automation checks your ID in minutes, not days.
- Smarter alerts. Overdraft and low-balance warnings arrive before trouble.
- More relevant offers. Personalized banking surfaces useful products, not random ones.
AI in Digital Banking Security: How Fraud Detection Actually Works
AI in digital banking security is one of the clearest wins for everyday users. Fraud detection AI builds a profile of your normal activity — your usual stores, amounts, and devices. When something looks off, it scores the risk and may ask for a quick verification check.
This matters because the old rule-based systems were easy to game. Modern AI spots patterns that rigid rules never could. That said, it isn’t perfect, and some of the fastest-growing fraud types in 2026 bypass even the best detection systems. This is a deep topic on its own. For the full breakdown, read our guide on AI fraud detection in finance.
KYC Automation: Why Account Opening Now Takes Minutes
KYC automation means “Know Your Customer” checks run by AI. It scans your document, checks for tampering, and screens against watchlists. This is why opening an account is so fast now — what used to take days of manual review now takes minutes.
Mini takeaway: The best AI features save you time and catch problems you’d miss.
The Risks of AI in Banking for Consumers
AI in banking isn’t all upside. Here’s what to watch — without the fear-mongering.
AI May Influence Your Credit — and You May Not Know It
AI is increasingly used to assess creditworthiness. That raises a fair question: can the bank explain the decision?
Regulators are paying attention. The EU AI Act classifies AI used in credit scoring as “high-risk,” which means human oversight and explainability are required. US rules are still forming, but the direction is similar.
If you’re denied credit and something feels off, you can ask what role AI played. You’re entitled to a real reason, not “the algorithm decided.”
Oversight and Governance Vary Widely
Some banks build AI with strong human review. Others don’t. Clear governance is now a sign of a trustworthy product, and one of the underappreciated risks of AI in banking is that consumers often have no way to tell the difference from the outside.
The NIST AI Risk Management Framework gives institutions a voluntary model for responsible AI. It’s a useful benchmark when you judge a bank’s claims.
Your Data and Privacy
Connecting apps to your account expands your data footprint. That’s a trade-off worth understanding before you link anything. We cover this in detail in our guide on AI financial data privacy.
Lending and Approval Models
AI lending can widen access, but it can also encode bias if built carelessly. If you use buy-now-pay-later or AI-driven approvals, it helps to know how the model works. See BNPL and AI risk assessment for a closer look.
Mini takeaway: The risk isn’t AI itself. It’s opaque decisions made without explanation or a path to appeal.
How to Judge an AI Banking Feature
Here’s a quick checklist before you trust any AI-driven banking tool.
- What does the AI actually do? Fraud detection, credit scoring, conversational banking support, or just a basic script?
- Is there a human option? You should be able to reach a real person for hard cases.
- Can it explain decisions? Especially for credit or fraud flags.
- How is your data used? Look for clear, specific language, not vague promises.
- Are your deposits protected? Confirm the bank or its partner is FDIC-insured.
On that last point, many neobanks partner with insured banks. The FDIC deposit insurance FAQs explain that coverage generally reaches $250,000 per depositor, per insured bank, per ownership category. Always verify the specific partner bank before you deposit.
Do This vs. Avoid This
- Do choose banks that clearly state when AI is involved in decisions.
- Do keep an eye on connected apps and remove ones you no longer use.
- Avoid apps that ask for your actual bank login instead of secure API access.
- Avoid assuming “bank-level security” means anything specific. Ask for detail.
The Future of AI in Banking
The future of AI in banking isn’t about replacing your bank. It’s about embedding smarter decisions into every touchpoint — from the moment you apply for an account to how disputes get resolved years later.
Intelligent banking automation will get more capable. Conversational banking will get more natural. Generative AI in banking will start to handle tasks that once required a financial advisor. Some banks are already testing digital humans in banking — AI-powered video interfaces that mimic in-branch conversations for complex questions.
The shift is real. But so is the need for transparency, clear governance, and consumer protections that keep pace with the technology. What separates trustworthy banks from the rest will be whether they can explain what their AI is doing — not just that it’s doing something.
Frequently Asked Questions
How Has AI Changed Digital Banking for Everyday Consumers?
AI has moved from back-office automation to real-time tools you use daily. Fraud detection, dispute resolution, overdraft warnings, and some credit decisions now run on AI, often before you contact support. The result is faster, more personalized banking — and the beginning of true conversational banking for everyday users.
What Are the Best Neobanks Using AI for Personal Finance?
Chime leads in support automation and fraud reduction. Monzo builds tax tools for freelancers. Starling offers a scam-check tool. Revolut is developing a proactive financial companion. The best choice depends on your specific needs, not rankings alone.
What’s the Difference Between Chatbot Banking and Real AI?
A chatbot follows a script and can’t reason. Real AI in digital banking — often called conversational banking when customer-facing — analyzes your full account history and behavior. It acts before you ask and adapts to your habits instead of following a one-size-fits-all rule set.
What Are the Biggest Risks of AI in Banking for Consumers?
The main risks include opaque credit decisions with no clear explanation, inconsistent human oversight across institutions, data privacy trade-offs from connected apps, and the growing risk of authorized fraud that AI detection systems can’t always catch. Understanding these risks helps you ask better questions before you trust a new banking tool.
Is an AI Neobank Safe to Use?
Many AI neobanks partner with FDIC-insured banks, so your deposits may carry standard protection. Verify the specific partner bank and account structure first. The FDIC covers up to $250,000 per depositor, per insured bank, per ownership category. Always confirm before depositing.
What Is the Most Effective AI for Online Banking Right Now?
The most effective AI for online banking combines real-time fraud detection, behavioral risk scoring, and personalized alerts — all running before you notice a problem. Banks using behavioral biometrics and machine learning fraud models consistently outperform those relying on older rule-based systems.
What Is KYC Automation in Banking?
KYC automation uses AI to verify your identity when you open an account. It scans your documents, checks for tampering, and screens against watchlists. This is why account opening now takes minutes instead of days and is a core part of how banking automation trends are reshaping the industry.
What Is Intelligent Automation in Banking?
Intelligent automation in banking combines AI and process automation to handle complex tasks at scale — think fraud triage, document review, compliance checks, and dispute processing. Unlike simple rule-based automation, it can adapt to new patterns and learn from outcomes over time.
The Bottom Line
AI in digital banking is already here, running quietly inside your account. It protects you from fraud, speeds up disputes, and personalizes your experience. The banks doing it well rarely make noise about it.
Your job as a user is simple. Understand what the AI does, ask for transparency, and confirm your deposits are protected. The right setup works harder for you than any system you’ve had before.
Your next step: Check what AI features your current bank offers. If fraud protection is still rule-based, disputes take days, or you can’t reach a human, it may be time to compare options. For the wider context, start with our guide on fintech trends in 2026.
This post is for informational purposes only. It is not financial or legal advice. AI banking features and rules change often, so always verify directly with your financial institution before making account decisions.
AI in Digital Banking · Editorial Integrity
Sources & Citations
Public frameworks, regulatory guidance, and current reporting behind this guide to AI in digital banking — covering how banks and neobanks use AI, fraud detection, KYC automation, credit decisioning, open banking, deposit protection, and AI governance.
This guide is grounded in public regulatory frameworks, government guidance, and current industry documentation on how AI runs inside everyday banking. We prioritized official sources for consumer data rights, AI governance, and deposit protection, then used them to frame how banks and neobanks deploy AI for fraud detection, identity checks, and credit decisions. Because banking rules, product capabilities, and AI oversight evolve quickly, readers should verify the latest rules, partner-bank details, and vendor claims before making account or financial decisions.
View full sources, methodology, and editorial notes
This article was developed using primary regulatory materials, government guidance, and named institutional frameworks relevant to AI in consumer banking. We favor official policy sources, agency guidance, and recognized standards when explaining open banking, AI governance, fraud risk, identity verification, credit decisioning, and deposit protections. Supporting article references are included where they extend a topic discussed in the guide. This article is educational information and should not be treated as legal, financial, compliance, or investment advice.
- Consumer-authorized data access and open banking: CFPB — Personal Financial Data Rights — cited for the article’s explanation of secure, consumer-authorized data sharing and how open banking shapes connected banking apps and account access.
- AI governance and risk management framework: NIST — AI Risk Management Framework — cited for the oversight, explainability, and trustworthy-AI principles referenced in the article’s discussion of responsible AI in digital banking.
- European rules for high-risk AI systems: EU AI Act — cited for the regulatory context around AI used in credit scoring and financial decisions, including human oversight and explainability expectations.
- Deposit protection and neobank account safety: FDIC — Deposit Insurance FAQ — cited for the article’s explanation of deposit insurance limits and partner-bank account structures relevant to neobank users.
- Behavior-based fraud detection in finance: Tech Capital Hub — AI Fraud Detection in Finance — cited as a supporting internal source for the article’s discussion of behavior-based fraud models and modern payment risk controls.
- AI-powered underwriting and credit decisioning: Tech Capital Hub — BNPL and AI Risk Assessment — cited as a supporting internal source for the section on AI-driven credit decisions, real-time approvals, and alternative risk models.
- Data rights, permissions, and privacy risk: Tech Capital Hub — AI Financial Data Privacy — cited as a supporting internal source for the governance, permissions, and trust issues tied to connecting apps to bank accounts.
- Broader fintech context and market trends: Tech Capital Hub — Fintech Trends 2026 — cited as the related pillar reference for the wider forces shaping AI, banking, and payments in 2026.
AI in Digital Banking · Editorial Standards
Our Editorial Standards
Tech Capital Hub applies Google’s E-E-A-T framework to every banking and AI guide, emphasizing practical clarity, public documentation, and verifiable sources over hype. This article draws on trusted frameworks where they support specific claims — CFPB materials for consumer-authorized data access and open banking, the NIST AI Risk Management Framework for governance and oversight, the EU AI Act for high-risk AI used in credit decisions, and FDIC guidance for deposit protection relevant to neobank accounts. Where AI adoption, product behavior, or regulation is still evolving, we describe the direction of change carefully rather than overstate certainty.
View how our editorial standards apply to this article
Written for Everyday Account Holders
This article is structured for people who actually use banking apps, not just industry insiders. Instead of listing buzzwords, it explains how AI shows up in your account today — faster disputes, overdraft warnings, fraud flags, and quicker approvals — and what each change means in practice. The goal is to help real customers understand the tools running behind their money and decide what to trust.
Banking AI Explained in Plain Language
The guide breaks down difficult topics — behavior-based fraud detection, KYC automation, personalized banking, and AI-driven credit decisions — into language that stays precise without becoming overly technical. It also separates the visible features you touch from the invisible decision systems underneath, so readers can see where the real shift in digital banking is happening.
Primary Frameworks and Named Sources Over Vague Claims
Specific claims are anchored to recognized public sources where possible. Open banking and data-rights context draws on CFPB guidance, AI oversight and explainability reference the NIST AI Risk Management Framework and the EU AI Act, and deposit protection for neobank users references FDIC guidance. We point to supporting internal analysis only where it meaningfully extends a topic already introduced in the article.
Clear About Uncertainty, Risk, and Limits
Digital banking changes quickly, and responsible coverage should say so. This guide avoids promising outcomes, avoids treating vendor claims as proof, and distinguishes regulatory direction from settled consensus — especially around AI credit decisions and account protections. It is educational information, not legal, compliance, investment, or financial advice. Always verify partner-bank details and current terms before making account decisions. Corrections or source questions can be sent to the editorial team.
AI in Digital Banking · About the Author
James Whitfield
Senior Fintech Editor & Analyst · Tech Capital Hub
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering where AI, digital banking, and payment infrastructure meet. In this guide, he breaks down how banks and neobanks actually use AI today — from fraud detection and KYC automation to personalized banking and credit decisions — and what it means for everyday account holders.
View full author bio, credentials, and links
James Whitfield is a Senior Fintech Editor & Analyst at Tech Capital Hub with eight years of experience covering where AI, digital banking, and payment infrastructure meet. He writes for everyday banking customers and finance leaders who want to understand what an AI-driven feature actually does once it leaves the marketing page and starts making decisions inside a real account.
His reporting focuses on the practical side of digital banking: how behavior-based fraud detection flags suspicious activity, how KYC automation speeds up account opening, how personalized banking tools act before problems happen, and how AI increasingly shapes credit decisions. For this article, James explains how banks and neobanks deploy AI behind the scenes, separates the features users see from the decision systems running underneath, and weighs the benefits against the real questions around transparency, oversight, and data rights. All articles are educational information and should not be treated as financial, legal, compliance, or investment advice.
- Covers AI in digital banking through the lens of real account-holder impact, not surface-level trend reporting
- Explains fraud detection, KYC automation, personalized banking, and AI credit decisions in plain language
- Tracks how banking tools perform in live conditions, including oversight, risk controls, and operational trade-offs
- Separates genuine AI capability from marketing claims using technical, regulatory, and user-outcome lenses
- Grounds analysis in public frameworks, named sources, and clear editorial standards with educational framing
Enjoying our content?
Click below to add us as a preferred source. Google will prioritize our latest articles in your Top Stories, AI Mode, and AI Overviews.
Preferred Source on Google